Registrieren Ice Fishing: Internationale Zusammenarbeit im Glücksspielbereich

Die Welt des Online-Glücksspiels bietet unzählige Möglichkeiten für Unterhaltung und potenzielle Gewinne, doch sie birgt auch Risiken. Um verantwortungsbewusste Spieler zu schützen, haben sich verschiedene Sperrsysteme etabliert, darunter die OASIS Spielsperre. Dieses grenzüberschreitende System ermöglicht es Spielern, sich selbst von Online-Casinos und Wettplattformen zu sperren, um Spielsucht vorzubeugen. Für diejenigen, die nach vertrauenswürdigen Alternativen suchen, bieten siti scommesse oft robuste Sicherheitsfeatures. Plattformen wie migliori siti scommesse priorisieren den Spielerenschutz und ermöglichen es Nutzern, ihre Limits festzulegen oder eine Selbstsperre zu aktivieren. Die Betreiber von bookmaker online verstehen zunehmend die Bedeutung solcher Schutzmaßnahmen, was für eine gesunde Branche von entscheidender Bedeutung ist.
Online Casino: Spielautomaten und Live-Spiele im Überblick

Die OASIS Spielsperre ist ein wichtiges Instrument im Kampf gegen problematisches Glücksspiel. Als grenzüberschreitendes Sperrsystem ermöglicht es Spielern aus verschiedenen Ländern, sich auf einer zentralen Liste eintragen zu lassen. Dies bedeutet, dass eine Sperre in einem Land auch in anderen teilnehmenden Nationen anerkannt wird. Für Nutzer von siti scommesse online bietet dies zusätzliche Sicherheit, da sie nicht einfach zu einer anderen Plattform wechseln können, um der Sperre zu entgehen. Details zu Bonusbedingungen und Spielauswahl gibt es direkt bei registrieren Ice Fishing. Die Zusammenarbeit zwischen siti di scommesse sportive über Landesgrenzen hinweg wird immer wichtiger, um einen effektiven Spielerenschutz zu gewährleisten. Wenn Sie die Welt des Online-Glücksspiels erkunden, ist es entscheidend, Plattformen zu wählen, die verantwortungsbewusste Praktiken fördern.

Viele moderne siti scommesse bonus-Anbieter integrieren bereits solche grenzüberschreitenden Sperrsysteme in ihre Sicherheitsprotokolle. Wenn Sie die Welt des Online-Glücksspiels erkunden, ist es entscheidend, Plattformen zu wählen, die verantwortungsbewusste Praktiken fördern. Ein Besuch auf einem vertrauenswürdigen Portal wie ice-fishing-casino-de.com kann Ihnen helfen, seriöse Anbieter zu identifizieren, die solche Schutzmechanismen aktiv anwenden. Die Zusammenarbeit zwischen Regulierungsbehörden und Casino-Betreibern ist unerlässlich, um ein sicheres und faires Umfeld für alle Spieler zu schaffen. Einige Plattformen bieten darüber hinaus Tools zur Selbsteinschätzung des Spielverhaltens.

Die Bedeutung von OASIS als grenzüberschreitendes Sperrsystem

Was ist die OASIS Spielsperre?

OASIS steht für “Online Access Self-Exclusion International System” und ist ein grenzüberschreitendes Sperrsystem, das Spielern aus verschiedenen Ländern ermöglicht, sich selbst von Online-Glücksspielplattformen auszuschließen. Das System wurde entwickelt, um Spielern zu helfen, die Kontrolle über ihr Spielverhalten zurückzugewinnen und problematisches Spielen zu verhindern. Durch die zentrale Erfassung der gesperrten Personen können Betreiber von siti scommesse die Sperre wirksam umsetzen, unabhängig davon, von welchem Land aus der Spieler auf die Plattform zugreift. OASIS gilt als eines der fortschrittlichsten Selbstsperre-Systeme weltweit.

Wie funktioniert das System?

Die Funktionsweise von OASIS ist relativ einfach: Spieler können sich freiwillig für eine bestimmte Zeitdauer (in der Regel mindestens sechs Monate) selbst sperren. Während dieser Sperrzeit ist ihnen der Zugriff auf alle teilnehmenden Online-Casinos und migliori siti scommesse verwehrt. Die Daten der gesperrten Personen werden in einer zentralen Datenbank gespeichert, auf die die Betreiber von bookmaker online zugreifen können. Dies verhindert, dass Spieler während der Sperrzeit neue Konten bei anderen Plattformen eröffnen können, was ein wesentlicher Vorteil gegenüber nationalen Systemen darstellt. Die Umsetzung erfolgt über die Registrierung bei einer nationalen Anlaufstelle, die die Daten an OASIS weiterleitet.

Vorteile der grenzüberschreitenden Sperre

Effektiver Schutz vor Umgehung

Einer der größten Vorteile von OASIS ist die Verhinderung von Umgehungsversuchen. Bei nationalen Sperrsystemen können Spieler oft einfach zu Plattformen in anderen Ländern wechseln, um ihre Sperre zu umgehen. Mit OASIS ist dies nicht mehr möglich, da die Sperre international anerkannt wird. Für Betreiber von siti scommesse online bedeutet dies weniger administrative Belastung, da sie nur eine Sperre überprüfen müssen, statt nationale Regelungen verschiedener Länder zu kennen und umzusetzen. Dies schafft eine einheitlichere und effektivere Schutzgrundlage für alle Beteiligten.

Erhöhte Sicherheit für Spieler

Für Spieler bietet OASIS eine zusätzliche Sicherheitsebene. Die Kenntnis, dass eine Sperre in allen teilnehmenden Ländern gültig ist, kann eine stärkere abschreckende Wirkung haben. Spieler, die ernsthaft ihr Spielverhalten ändern möchten, finden in solchen Systemen eine verlässliche Unterstützung. Viele siti di scommesse sportive integrieren zusätzlich zu OASIS eigene Sicherheitsmaßnahmen wie Verifizierung von Spielern, Limits für Einzahlungen und Spielzeiten sowie Warnsysteme bei riskantem Verhalten. Diese Kombination aus internationaler und nationaler Ebene schafft einen umfassenden Schutzmechanismus.

Die Rolle der Online-Casinos beim Spielerenschutz

Eigene Sicherheitsmaßnahmen

Zusätzlich zu OASIS bieten seriöse Online-Casinos eigene Sicherheitsmaßnahmen, um Spieler zu schützen. Dazu gehören Tools zum Festlegen von Einzahlungslimits, Spielzeitbegrenzungen und Verifizierungen der Spieleridentität. Viele siti scommesse bonus-Anbieter bieten auch die Möglichkeit einer permanenten Selbstsperre oder eine zeitlich begrenzte Ausschlussfrist. Diese zusätzlichen Maßnahmen sind besonders wichtig, da OASIS eine freiwillige Selbstsperre ist und nur wirksam ist, wenn der Spieler tatsächlich Hilfe sucht. Einige Casinos offerieren zudem Mitarbeiter, die speziell für die Betreuung von Spielern mit problematischem Verhalten geschult wurden.

Verantwortungsvolles Marketing

Ein weiterer Aspekt des SpielerSchutzes ist verantwortungsvolles Marketing. Seriöse migliori siti scommesse verzichten auf aggressive Werbung, die insbesondere an vulnerable人群 wie Minderjährige oder Suchtkranke gerichtet ist. Stattdessen setzen sie auf informative Inhalte, die über die Risiken des Glücksspiels aufklären und Hilfsangebote bereitstellen. Die Betreiber von bookmaker online verstehen zunehmend, dass langfristiger Erfolg nur durch ethisches Handeln und verantwortungsbewusste Geschäftspolitik möglich ist. Einige Unternehmen investieren sogar gezielt in Präventionsprogramme und Finanzierung von Beratungsstellen.

Internationale Zusammenarbeit im Glücksspielbereich

Gemeinsame Regulierungsstandards

Die Einführung von OASIS zeigt die zunehmende internationale Zusammenarbeit im Glücksspielbereich. Regulierungsbehörden aus verschiedenen Ländern arbeiten zusammen, um gemeinsame Standards für den Spielerenschutz zu entwickeln. Diese Zusammenarbeit erstreckt sich auch auf den Austausch von Informationen über verdächtige Aktivitäten und betrügerische Praktiken. Für siti scommesse online bedeutet dies, dass sie sich an strengere Richtlinien halten müssen, was im Endeffekt den Spielern zugutekommt. Solche Kooperationen helfen auch bei der Bekämpfung illegaler Glücksspielangebote.

Harmonisierung der rechtlichen Rahmenbedingungen

Ein weiteres Ziel der internationalen Zusammenarbeit ist die Harmonisierung der rechtlichen Rahmenbedingungen. Während die nationalen Gesetze weiterhin variieren, gibt es Bestrebungen, grundlegende Prinzipien für den Glücksspielmarkt zu etablieren. Dazu gehören Standards für Spielerverifikation, Geldwäscheprevention und Spielerschutz. Viele siti di scommesse sportive unterstützen diese Bestrebungen, da sie zu einem fairen und transparenten Markt beitragen und das Vertrauen der Spieler stärken. Eine harmonisierte Regulierung könnte langfristig auch zu besserem Verbraucherschutz und fairen Wettbedingungen führen.

Technische Aspekte der OASIS-Implementierung

Datenschutz und Sicherheit

Eine der größten Herausforderungen bei der Implementierung von OASIS ist der Umgang mit sensiblen Spielerdaten. Das System stellt sicher, dass alle personenbezogenen Daten sicher werden und gemäß den europäischen Datenschutzbestimmungen wie der DSGVO verarbeitet werden. Die Sicherheit der Daten ist von entscheidender Bedeutung, da sie sensible Informationen über die Spieler enthalten. Die siti scommesse müssen strenge Sicherheitsprotokolle einhalten, um die Daten der gesperrten Spieler zu schützen und unbefugten Zugriff zu verhindern. Regelmäßige Audits und Sicherheits

Woran man ein seriöses Online Casino erkennt

Kriterium Warum es zählt
Lizenz Legale Angebote stehen unter deutscher oder EU-Aufsicht
Auszahlungsquote Faire Slots veröffentlichen ihre RTP-Werte
Bonusbedingungen Umsatzbedingungen zählen mehr als der Bonusbetrag
Auszahlungsdauer Schnelle Auszahlungen zeigen finanzielle Stabilität
Kundendienst Deutscher Support hilft bei Problemen sofort weiter

Häufige Fragen

Wie lange dauern Auszahlungen im Online Casino?
Bei seriösen Anbietern dauert eine Auszahlung mit geprüften Zahlungsmethoden in der Regel ein bis drei Werktage.

Was bedeutet die Umsatzbedingung bei einem Bonus?
Der Bonusbetrag muss mehrfach im Casino eingesetzt werden, bevor Gewinne zur Auszahlung freigegeben werden.

Was tun, wenn Spielen zum Problem wird?
Sofortige Einzahlungslimits oder eine Spielsperre über OASIS setzen und Beratungsstellen wie die BZgA nutzen.
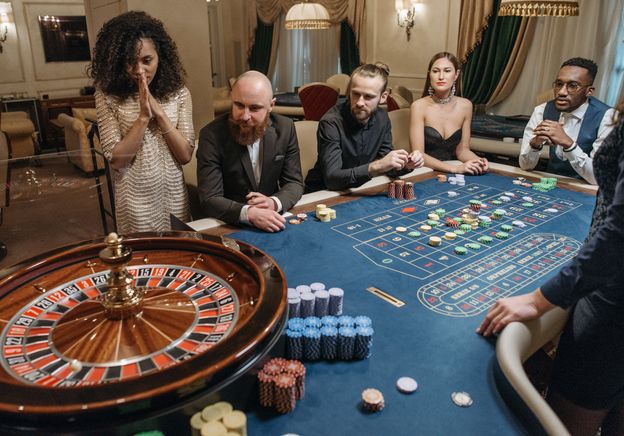
Registrieren Alawin: Die Anfänge des Glücksspiels in Deutschland

Die Welt der deutschen Spielbanken hat eine reiche und faszinierende Geschichte, die sich über Jahrhunderte erstreckt und sich ständig weiterentwickelt. Was einst exklusive Luxusorte für Adelige und Wohlhabende waren, hat sich im digitalen Zeitalter zu einem massenattraktiven Unterhaltungsmittel gewandelt. Heute können Glücksspieler bequem von zu Hause aus ihre favorisierten Spiele genießen, während die traditionellen Casinos weiterhin ihren besonderen Charme bewahren. Die Entwicklung dieser faszinierenden Branche spiegelt nicht nur technologischen Fortschritt wider, sondern auch gesellschaftliche Veränderungen und die deutsche Einstellung zum Glücksspiel. Für diejenigen, die die digitale Variante erkunden möchten, ist es immer ratsam, sich über die aktuellen Angebote zu informieren, einschließlich der Möglichkeit, sich zu registrieren Alawin für einen erstklassigen Spielgenuss.

Die Anfänge des Glücksspiels in Deutschland

Die Ursprünge des Glücksspiels in Deutschland lassen sich bis ins Mittelalter zurückverfolgen, wo einfare Spiele und Wetten schon damals eine beliebte Unterform darstellten. Die ersten organisierten Spielbanken entstanden jedoch erst im 17. und 18. Jahrhundert in deutschen Ländern und wurden oft von Fürstenhösten betrieben, die diese als zusätzliche Einnahmequelle für ihre Kassen nutzten. Diese frühen Einrichtungen dienten nicht nur dem Spiel, sondern auch als gesellschaftliche Treffpunkte für die Oberschicht.

Barocke Pracht und höfische Unterhaltung

Im Barockzeitalter erlebten Spielbanken in deutschen Residenzstädten wie Würzburg oder Dresden ihre erste Blütezeit. Diese Häuser waren prachtvoll ausgestattet und boten nicht nur Glücksspiele, sondern auch Veranstaltungen aller Art. Das bekannteste aus dieser Zeit ist das kurfürstliche Casino in Bad Ems, das als erstes deutsches Casino gilt und bereits 1720 eröffnet wurde. Erfahrungsberichte zu registrieren Alawin liefern eine erste Orientierung im deutschen Markt. Die Atmosphäre war exklusiv und streng kontrolliert, was dem Glücksspiel einen Hauch von Legitimität verlieh.

Die Napoleonische Ära und ihre Auswirkungen

Napoleons Feldzüge brachten nicht nur politische Veränderungen, sondern auch die Modernisierung des Glücksspiels nach Deutschland. Französische Spielkonzepte und neue Spiele wie Roulette und Blackjack fanden Eingang in deutsche Spielbanken. Diese Zeit markierte einen Wendepunkt, da das Glücksspiel zunehmend aus dem höfischen Umfeld heraus und in die bürgerliche Gesellschaft vordrang, was später zur Regulierung führen sollte.

Das 19. Jahrhundert: Regulierung und Blüte

Das 19. Jahrhundert war für die deutschen Spielbanken eine Zeit der Regulierung und gleichzeitig ihrer größten Blüte. Viele Länder erließen eigene Glücksspielgesetze, um den Betrieb zu kontrollieren und Einnahmen zu sichern. Baden-Baden, Bad Homburg und Wiesbaden avancierten zu europaweit bekannten Kurorten mit eleganten Spielcasinos, die aristokratische Gäste aus ganz Europa anzogen.

Baden-Baden: Das Monte Carlo des Nordens

Das Casino Baden-Baden, 1809 eröffnet, entwickelte sich schnell zum vornehmsten Spielhaus Deutschlands. Unter der Leitung von François Blanc, der auch das Casino Monte Carlo aufbaute, erlebte es seine Glanzzeit. Das prunkvolle Ambiente, strenge Etikette und exklusive Spiele machten es zum Treffpunkt von Hochadel und wohlhabendem Bürgertum. Selbst Dichter wie Fjodor Dostojewski, der in seinem Roman “Der Spieler” das Kasinoleben beschrieb, waren regelmäßige Gäste.

Die rechtliche Entwicklung im Deutschen Reich

Mit der Gründung des Deutschen Reiches 1871 wurde die Regulierung des Glücksspiels komplexer. Während einige Länder wie Preußen das Glücksspiel verboten, erlaubten andere wie Hessen oder Bayern den Betrieb staatlicher Monopolcasinos. Diese Zweiteilung prägte die deutsche Glücksspiellandschaft bis weit ins 20. Jahrhundert und schuf ein Nebeneinander von legalen und illegalen Spielangeboten.

20. Jahrhundert: Verbot, Wende und Neuanfang

Das 20. Jahrhundert brachte für die deutschen Spielbanken turbulente Zeiten mit sich. Nach dem Ersten Weltkrieg verschärften sich die Maßnahmen gegen das Glücksspiel, während es in den 1920er Jahren in der Weimarer Republik eine kurze, aber heftige Blüte erlebte. Der Nationalsozialismus verbot 1933 sämtliche Glücksspiele, was das Ende der traditionellen Spielbankenzeit einläutete.

Nachkriegszeit und Wiederaufbau

Erst 1953 mit der Fertigstellung des Casinos in Bad Kissingen begann die vorsichtige Wiederbelebung des Glücksspiels in Westdeutschland. Die Alliierten erlaubten zunächst nur beschränkte Spielangebote, was sich jedoch schnell änderte. 1955 wurde das erste moderne Casino nach Kriegsende in Bad Reichenhall eröffnet, gefolgt von weiteren Häusern in bekannten Kurorten.

Die Teilung Deutschlands und ihre Auswirkungen

Die Teilung Deutschlands nach dem Zweiten Weltkrieg führte zu unterschiedlichen Entwicklungen. Während in der Bundesrepublik die traditionellen Spielbanken wiedereröffnet wurden, verbot die DDR jegliches Glücksspiel. Diese unterschiedliche Behandlung spiegelte die unterschiedlichen Gesellschaftsmodelle wider und prägte die Glücksspiellandschaft bis zur Wiedervereinigung 1990.

Ära der Liberalisierung: Neue Gesetze und moderne Casinos

Ab den 1970er Jahren begann eine Phase der Liberalisierung, die die deutsche Glücksspiellandschaft grundlegend veränderte. Neue Gesetze schafften rechtliche Grundlagen für den Casino-Betrieb, während modernere Konzepte und Spielangebote eingeführt wurden. Diese Entwicklung machte deutsche Casinos wieder attraktiver und führte zu einer neuen Blütezeit.

Die Einführung des Konzessionssystems

Ein wichtiger Meilenstein war die Einführung des staatlichen Konzessionssystems, das den Betrieb von Spielbanken streng reguliert. Nur wenige Unternehmen erhalten eine Lizenz, was Qualität und Sicherheit garantieren soll. Dieses System existiert bis heute und stellt sicher, dass nur seriöse Anbieter am Markt tätig sein dürfen.

Internationalisierung und Wettbewerb

Mit der zunehmenden Internationalisierung des Glücksspiels mussten auch deutsche Casinos mit internationalen Standards mithalten. Moderne Technologien, gehobene Einrichtungen und exzellenter Service wurden entscheidende Erfolgsfaktoren. Gleichzeitig stieg auch der Druck von ausländischen Casinos, die deutsche Kunden anzuziehen, was zu einer Intensivierung des Wettbewerbs führte.

Die digitale Revolution: Online Casinos in Deutschland

Das 21. Jahrhundert brachte mit dem Internet eine Revolution für die Glücksspielbranche. Deutsche Spieler entdeckten Online-Casinos für sich, was zu einem Boom führte. Trotz anfänglicher rechtlicher Unsicherheit etablierten sich virtuelle Spielhäuser parallel zu den traditionellen Casinos, wobei die beiden Formate heute oft nebeneinander bestehen.

Rechtliche Herausforderungen im digitalen Zeitalter

Die Entwicklung von Online-Glücksspielen in Deutschland verlief rechtlich kompliziert. Lange Zeit herrschte eine rechtliche Grauzone, die erst mit dem neuen Glücksspielstaatsvertrag 2021 eine klare Regelung erhielt. Dieser erlaubt erstmals seit 2012 wieder lizenzierte Online-Anbieter, schafft aber strenge Rahmenbedingungen für den Betrieb.

Zukunftsperspektiven und technologische Innovationen

Die Zukunft deutscher Glücksspiellandschaft wird von technologischen Innovationen geprägt sein. Virtuelle Realität, Live-Casinos und mobile Gaming-Optionen verändern das Spielerlebnis grundlegend. Gleichzeitig entwickeln sich immer mehr Plattformen zu Unterhaltungszentren, die nicht nur Glücksspiele, sondern auch Social Features und weitere digitale Inhalte anbieten. Für Interessierte, die diese digitale Welt erkunden möchten, bietet sich die Gelegenheit, sich online zu registrieren Alawin für einen modernen und sicheren Spielgenuss, der die Tradition deutscher Casino-Kultur mit den Möglichkeiten des digitalen Zeitalters verbindet. Die Vielfalt der verfügbaren Optionen spiegelt sich auch in den zahlreichen Online-Plattformen wider, die unterschiedliche Schwerpunkte haben und von Spielern genutzt werden können.

Tradition und Moderne: Die Doppelgesichtigkeit der deutschen Casino-Kultur

Heute zeichnet sich die deutsche Glücksspiellandschaft durch eine interessante Dualität aus: Einerseits die traditionellen Spielbanken mit ihrem historischen Charme, andererseits die modernen Online-Plattformen. Diese Entwicklung spiegelt gesellschaftliche Veränderungen wider und zeigt, wie das Glücksspiel im digitalen Zeitalter neue Formen annimmt, ohne seine Faszination zu verlieren.

Die historische Entwicklung der deutschen Spielbanken

Woran man ein seriöses Online Casino erkennt

Kriterium Warum es zählt
Lizenz Legale Angebote stehen unter deutscher oder EU-Aufsicht
Auszahlungsquote Faire Slots veröffentlichen ihre RTP-Werte
Bonusbedingungen Umsatzbedingungen zählen mehr als der Bonusbetrag
Auszahlungsdauer Schnelle Auszahlungen zeigen finanzielle Stabilität
Kundendienst Deutscher Support hilft bei Problemen sofort weiter

Häufige Fragen

Was tun, wenn Spielen zum Problem wird?
Sofortige Einzahlungslimits oder eine Spielsperre über OASIS setzen und Beratungsstellen wie die BZgA nutzen.

Sind Gewinne aus dem Online Casino steuerfrei?
In Deutschland bleiben Glücksspielgewinne für private Spieler grundsätzlich steuerfrei, weil auf Einsätze bereits Abgaben erhoben werden.

Wie lange dauern Auszahlungen im Online Casino?
Bei seriösen Anbietern dauert eine Auszahlung mit geprüften Zahlungsmethoden in der Regel ein bis drei Werktage.

Registrieren Alawin: Die Anfänge des Glücksspiels in Deutschland

Die Welt der deutschen Spielbanken hat eine reiche und faszinierende Geschichte, die sich über Jahrhunderte erstreckt und sich ständig weiterentwickelt. Was einst exklusive Luxusorte für Adelige und Wohlhabende waren, hat sich im digitalen Zeitalter zu einem massenattraktiven Unterhaltungsmittel gewandelt. Heute können Glücksspieler bequem von zu Hause aus ihre favorisierten Spiele genießen, während die traditionellen Casinos weiterhin ihren besonderen Charme bewahren. Die Entwicklung dieser faszinierenden Branche spiegelt nicht nur technologischen Fortschritt wider, sondern auch gesellschaftliche Veränderungen und die deutsche Einstellung zum Glücksspiel. Für diejenigen, die die digitale Variante erkunden möchten, ist es immer ratsam, sich über die aktuellen Angebote zu informieren, einschließlich der Möglichkeit, sich zu registrieren Alawin für einen erstklassigen Spielgenuss.

Die Anfänge des Glücksspiels in Deutschland

Die Ursprünge des Glücksspiels in Deutschland lassen sich bis ins Mittelalter zurückverfolgen, wo einfare Spiele und Wetten schon damals eine beliebte Unterform darstellten. Die ersten organisierten Spielbanken entstanden jedoch erst im 17. und 18. Jahrhundert in deutschen Ländern und wurden oft von Fürstenhösten betrieben, die diese als zusätzliche Einnahmequelle für ihre Kassen nutzten. Diese frühen Einrichtungen dienten nicht nur dem Spiel, sondern auch als gesellschaftliche Treffpunkte für die Oberschicht.

Barocke Pracht und höfische Unterhaltung

Im Barockzeitalter erlebten Spielbanken in deutschen Residenzstädten wie Würzburg oder Dresden ihre erste Blütezeit. Diese Häuser waren prachtvoll ausgestattet und boten nicht nur Glücksspiele, sondern auch Veranstaltungen aller Art. Das bekannteste aus dieser Zeit ist das kurfürstliche Casino in Bad Ems, das als erstes deutsches Casino gilt und bereits 1720 eröffnet wurde. Erfahrungsberichte zu registrieren Alawin liefern eine erste Orientierung im deutschen Markt. Die Atmosphäre war exklusiv und streng kontrolliert, was dem Glücksspiel einen Hauch von Legitimität verlieh.

Die Napoleonische Ära und ihre Auswirkungen

Napoleons Feldzüge brachten nicht nur politische Veränderungen, sondern auch die Modernisierung des Glücksspiels nach Deutschland. Französische Spielkonzepte und neue Spiele wie Roulette und Blackjack fanden Eingang in deutsche Spielbanken. Diese Zeit markierte einen Wendepunkt, da das Glücksspiel zunehmend aus dem höfischen Umfeld heraus und in die bürgerliche Gesellschaft vordrang, was später zur Regulierung führen sollte.

Das 19. Jahrhundert: Regulierung und Blüte

Das 19. Jahrhundert war für die deutschen Spielbanken eine Zeit der Regulierung und gleichzeitig ihrer größten Blüte. Viele Länder erließen eigene Glücksspielgesetze, um den Betrieb zu kontrollieren und Einnahmen zu sichern. Baden-Baden, Bad Homburg und Wiesbaden avancierten zu europaweit bekannten Kurorten mit eleganten Spielcasinos, die aristokratische Gäste aus ganz Europa anzogen.

Baden-Baden: Das Monte Carlo des Nordens

Das Casino Baden-Baden, 1809 eröffnet, entwickelte sich schnell zum vornehmsten Spielhaus Deutschlands. Unter der Leitung von François Blanc, der auch das Casino Monte Carlo aufbaute, erlebte es seine Glanzzeit. Das prunkvolle Ambiente, strenge Etikette und exklusive Spiele machten es zum Treffpunkt von Hochadel und wohlhabendem Bürgertum. Selbst Dichter wie Fjodor Dostojewski, der in seinem Roman “Der Spieler” das Kasinoleben beschrieb, waren regelmäßige Gäste.

Die rechtliche Entwicklung im Deutschen Reich

Mit der Gründung des Deutschen Reiches 1871 wurde die Regulierung des Glücksspiels komplexer. Während einige Länder wie Preußen das Glücksspiel verboten, erlaubten andere wie Hessen oder Bayern den Betrieb staatlicher Monopolcasinos. Diese Zweiteilung prägte die deutsche Glücksspiellandschaft bis weit ins 20. Jahrhundert und schuf ein Nebeneinander von legalen und illegalen Spielangeboten.

20. Jahrhundert: Verbot, Wende und Neuanfang

Das 20. Jahrhundert brachte für die deutschen Spielbanken turbulente Zeiten mit sich. Nach dem Ersten Weltkrieg verschärften sich die Maßnahmen gegen das Glücksspiel, während es in den 1920er Jahren in der Weimarer Republik eine kurze, aber heftige Blüte erlebte. Der Nationalsozialismus verbot 1933 sämtliche Glücksspiele, was das Ende der traditionellen Spielbankenzeit einläutete.

Nachkriegszeit und Wiederaufbau

Erst 1953 mit der Fertigstellung des Casinos in Bad Kissingen begann die vorsichtige Wiederbelebung des Glücksspiels in Westdeutschland. Die Alliierten erlaubten zunächst nur beschränkte Spielangebote, was sich jedoch schnell änderte. 1955 wurde das erste moderne Casino nach Kriegsende in Bad Reichenhall eröffnet, gefolgt von weiteren Häusern in bekannten Kurorten.

Die Teilung Deutschlands und ihre Auswirkungen

Die Teilung Deutschlands nach dem Zweiten Weltkrieg führte zu unterschiedlichen Entwicklungen. Während in der Bundesrepublik die traditionellen Spielbanken wiedereröffnet wurden, verbot die DDR jegliches Glücksspiel. Diese unterschiedliche Behandlung spiegelte die unterschiedlichen Gesellschaftsmodelle wider und prägte die Glücksspiellandschaft bis zur Wiedervereinigung 1990.

Ära der Liberalisierung: Neue Gesetze und moderne Casinos

Ab den 1970er Jahren begann eine Phase der Liberalisierung, die die deutsche Glücksspiellandschaft grundlegend veränderte. Neue Gesetze schafften rechtliche Grundlagen für den Casino-Betrieb, während modernere Konzepte und Spielangebote eingeführt wurden. Diese Entwicklung machte deutsche Casinos wieder attraktiver und führte zu einer neuen Blütezeit.

Die Einführung des Konzessionssystems

Ein wichtiger Meilenstein war die Einführung des staatlichen Konzessionssystems, das den Betrieb von Spielbanken streng reguliert. Nur wenige Unternehmen erhalten eine Lizenz, was Qualität und Sicherheit garantieren soll. Dieses System existiert bis heute und stellt sicher, dass nur seriöse Anbieter am Markt tätig sein dürfen.

Internationalisierung und Wettbewerb

Mit der zunehmenden Internationalisierung des Glücksspiels mussten auch deutsche Casinos mit internationalen Standards mithalten. Moderne Technologien, gehobene Einrichtungen und exzellenter Service wurden entscheidende Erfolgsfaktoren. Gleichzeitig stieg auch der Druck von ausländischen Casinos, die deutsche Kunden anzuziehen, was zu einer Intensivierung des Wettbewerbs führte.

Die digitale Revolution: Online Casinos in Deutschland

Das 21. Jahrhundert brachte mit dem Internet eine Revolution für die Glücksspielbranche. Deutsche Spieler entdeckten Online-Casinos für sich, was zu einem Boom führte. Trotz anfänglicher rechtlicher Unsicherheit etablierten sich virtuelle Spielhäuser parallel zu den traditionellen Casinos, wobei die beiden Formate heute oft nebeneinander bestehen.

Rechtliche Herausforderungen im digitalen Zeitalter

Die Entwicklung von Online-Glücksspielen in Deutschland verlief rechtlich kompliziert. Lange Zeit herrschte eine rechtliche Grauzone, die erst mit dem neuen Glücksspielstaatsvertrag 2021 eine klare Regelung erhielt. Dieser erlaubt erstmals seit 2012 wieder lizenzierte Online-Anbieter, schafft aber strenge Rahmenbedingungen für den Betrieb.

Zukunftsperspektiven und technologische Innovationen

Die Zukunft deutscher Glücksspiellandschaft wird von technologischen Innovationen geprägt sein. Virtuelle Realität, Live-Casinos und mobile Gaming-Optionen verändern das Spielerlebnis grundlegend. Gleichzeitig entwickeln sich immer mehr Plattformen zu Unterhaltungszentren, die nicht nur Glücksspiele, sondern auch Social Features und weitere digitale Inhalte anbieten. Für Interessierte, die diese digitale Welt erkunden möchten, bietet sich die Gelegenheit, sich online zu registrieren Alawin für einen modernen und sicheren Spielgenuss, der die Tradition deutscher Casino-Kultur mit den Möglichkeiten des digitalen Zeitalters verbindet. Die Vielfalt der verfügbaren Optionen spiegelt sich auch in den zahlreichen Online-Plattformen wider, die unterschiedliche Schwerpunkte haben und von Spielern genutzt werden können.

Tradition und Moderne: Die Doppelgesichtigkeit der deutschen Casino-Kultur

Heute zeichnet sich die deutsche Glücksspiellandschaft durch eine interessante Dualität aus: Einerseits die traditionellen Spielbanken mit ihrem historischen Charme, andererseits die modernen Online-Plattformen. Diese Entwicklung spiegelt gesellschaftliche Veränderungen wider und zeigt, wie das Glücksspiel im digitalen Zeitalter neue Formen annimmt, ohne seine Faszination zu verlieren.

Die historische Entwicklung der deutschen Spielbanken

Woran man ein seriöses Online Casino erkennt

Kriterium Warum es zählt
Lizenz Legale Angebote stehen unter deutscher oder EU-Aufsicht
Auszahlungsquote Faire Slots veröffentlichen ihre RTP-Werte
Bonusbedingungen Umsatzbedingungen zählen mehr als der Bonusbetrag
Auszahlungsdauer Schnelle Auszahlungen zeigen finanzielle Stabilität
Kundendienst Deutscher Support hilft bei Problemen sofort weiter

Häufige Fragen

Was tun, wenn Spielen zum Problem wird?
Sofortige Einzahlungslimits oder eine Spielsperre über OASIS setzen und Beratungsstellen wie die BZgA nutzen.

Sind Gewinne aus dem Online Casino steuerfrei?
In Deutschland bleiben Glücksspielgewinne für private Spieler grundsätzlich steuerfrei, weil auf Einsätze bereits Abgaben erhoben werden.

Wie lange dauern Auszahlungen im Online Casino?
Bei seriösen Anbietern dauert eine Auszahlung mit geprüften Zahlungsmethoden in der Regel ein bis drei Werktage.

Hyperliquid’s Order Book Transparency vs. CEX Dark Pools: Why Real-Time Visibility Changes Trading Strategy

A retail trader places a market order for 10 Bitcoin perpetuals on a centralized exchange. The order is instantly filled, but at a price that moved 15 basis points against them between the moment they clicked submit and execution. They do not know whether that slippage came from market movement, their broker’s routing decision, or a dark pool matching engine designed to extract value from retail flow. On Hyperliquid, the same order would execute against a fully visible on-chain order book where every bid, ask, and pending order is observable in real time by every participant. The execution price is not a surprise; it is a transparent outcome of supply and demand that can be verified before and after settlement.

That structural difference creates a material advantage for traders willing to understand it. Centralized exchanges have long relied on information opacity to manage order flow and optimize routing in their own interests. Their dark pools, internal matching engines, and opaque pricing create a zone where institutional traders with market-making arrangements and technology investments can extract consistent value from retail participants who cannot see what is actually happening underneath the trading interface. Hyperliquid’s hyperliquid-dex.com eliminates that asymmetry by making the order book itself a public resource. Every trader sees the same quotes, the same depth, and the same execution prices. The consequence is not free money. It is a level where skill, speed, and strategy matter more than information privilege.

How dark pools create invisible information asymmetry

A dark pool is a private trading venue operated by a centralized exchange or independent broker where orders are matched away from the public order book. On most major exchanges, a significant percentage of order flow—sometimes 30 to 50 percent—never touches the lit book. A retail trader entering a market order on Binance or Coinbase has no visibility into what portion of their order is being filled in a dark pool, at what price, or whether their flow is being sent to a market maker that benefits from seeing the order first.

The economic logic is straightforward. An exchange or broker operator has a financial incentive to internalize order flow because it creates a spread between what they pay the seller and charge the buyer. If they can match retail buy orders against retail sell orders without posting to a public book, they pocket the difference. If retail flow is imbalanced—more buyers than sellers, for example—they can route that flow to affiliated market makers who will fill it at a price slightly worse than the lit book but better than the retail trader might get elsewhere. The retail trader feels they got filled quickly and at a “reasonable” price. They do not see the alternative execution that was possible or the venue where their order actually settled.

This structure also creates a hidden information advantage. When a market maker on an exchange sees that large buy orders are coming into dark pools, they can adjust their public quotes upward before those buyers reach the lit book. By the time a retail trader’s limit order reaches the public order book, the price has already moved. The trader was outrun by an information signal they could not access. Institutional traders with co-location rights, direct exchange connections, and relationships with market makers benefit from seeing order flow patterns that retail participants cannot. The fee structure reinforces this: some exchanges charge less for high-volume traders or market makers and more for retail, directly subsidizing the information advantage.

Why fully transparent on-chain order books change the execution calculus

An on-chain order book operates on a completely different principle. Every order—bid, ask, cancellation, partial fill—is recorded on the blockchain in a transaction that every node validates and stores. There is no dark pool, no internal matching engine, and no hidden flow. When a trader places a limit order on Hyperliquid, that order becomes visible to all other participants immediately. They can see the exact price, the quantity, and the time it entered the book. When their own market order executes, they can see which orders it filled against and verify the prices on the blockchain itself.

This eliminates the information asymmetry in two ways. First, no participant has privileged early sight of orders. Everyone watching the blockchain sees orders at the same time. A market maker cannot route retail flow to themselves; their quotes are submitted to the same book as everyone else. Second, execution cannot be hidden. The transaction that fills an order is immutable and publicly queryable. A trader can verify the exact price they received and confirm that no better price was available at that moment on the book. There is no “best execution” argument because execution was transparent and deterministic.

The mechanics of this transparency also create behavioral effects. Because every limit order is visible, competitors can see what prices are defended and what gaps exist. This tends to reduce the spreads that market makers can maintain without being filled immediately. Because orders cannot be hidden until the moment of execution, traders cannot use dark pools to mask large positions. A trader building a large position must either move the market with visible orders or split their intentions across time. These are not slight improvements; they are fundamental structural differences that alter the risk-reward of various trading strategies.

Comparing liquidity depth: transparency versus convenience

The question many traders ask is whether a fully transparent, decentralized perpetual exchange can offer the same liquidity depth and spread quality as a centralized platform with years of market-maker relationships and order flow concentration. This is where CEX performance and DEX transparency must be evaluated together rather than treated as mutually exclusive. Hyperliquid has attracted significant liquidity because its transparent order book and zero trading fees eliminate the economic incentive for market makers to fragment their capital across multiple venues. If a market maker can operate on a fully transparent book with no fees and no custodial risk, they can afford to provide deeper quotes than they would on a platform where they compete against dark pools and information asymmetries.

The execution speed on Hyperliquid is designed to match or exceed CEX performance. The platform processes orders with sub-millisecond latency and settles them on-chain without requiring withdrawal or deposit delays between trades. A trader moving from a centralized exchange may initially feel that tighter spreads and faster execution are not guaranteed. However, the structure creates incentives for the opposite. A market maker on a transparent book serves the public at whatever spread they choose; if that spread is too wide, someone else will post a tighter quote. The competitive pressure is immediate and verifiable. On a centralized exchange, a market maker can widen spreads based on internalized order flow patterns that no one else can see.

The practical difference becomes visible during volatility. On a centralized exchange, spreads widen when volume surges because market makers reduce their size and the exchange’s dark pool matching engine can no longer fully hide large orders. On Hyperliquid, spreads can widen, but the widening happens at a single, transparent price level visible to all participants. No trader is surprised by a fill that disappeared into an opaque matching engine. The same market-making physics apply, but the information is distributed equally.

How retail traders can exploit on-chain visibility for execution advantage

The simplest advantage of transparent order book trading is order placement strategy. A retail trader can see exactly where liquidity sits and where gaps exist. If a perpetual contract for Ethereum is trading with $500,000 in bids at $2,350 and $400,000 in asks at $2,351, that trader knows exactly what they are bidding into or offering against. On a centralized exchange, the trader sees the public book but not the dark pool flow that might execute their order at a worse price. On Hyperliquid, what they see is what they get.

This visibility advantage compounds for limit orders. A trader can post a limit order to buy Bitcoin perps at a specific price and know that if their order is filled, it filled against orders actually posted to the visible book. They do not need to worry that their order was filled against a dark pool fill that would not have been available if the venue had been transparent. They also can observe when their orders are filled and by how much, allowing them to refine their pricing strategy in real time. If an order does not fill for several seconds, they can examine the order book and understand why.

For swing traders and position builders, on-chain visibility reveals something critical about order flow patterns. A trader watching the Hyperliquid order book for Bitcoin perpetuals can see when large orders are being accumulated by other participants. If bid-side depth suddenly increases, it suggests either new buyers entering or long positions being accumulated. If that same depth disappears quickly, it suggests positions being liquidated or closed. These are pure signals of market behavior that are valuable for directional decisions. On a centralized exchange, some of that signal is hidden in dark pools or is captured privately by the exchange’s own market makers.

Advanced traders can also use the transparent order book to execute large positions with minimal slippage. Instead of entering a market order that moves the price against them, they can observe the standing liquidity and decide whether to pick off small orders across multiple price levels or split their order across time. The blockchain records every trade, so a sophisticated trader can analyze historical patterns and optimize execution timing. This kind of analysis is available on centralized exchanges too, but on Hyperliquid it is based on transparent ground truth rather than whatever order flow the exchange chose to disclose.

The behavioral shift required to adapt from CEX to decentralized perpetual exchanges

A trader switching from a centralized exchange to a fully transparent decentralized perpetual exchange must adjust several habits. The first adjustment is accepting that the order book is the market, not a representation of it. On a centralized exchange, a trader mentally maps the visible book to some larger true market that includes dark pools. On Hyperliquid, the visible book is the complete market for that instrument. This is simpler in principle but requires a mindset shift. The trader must stop wondering if a better price exists elsewhere and start understanding that if it did, it would be on the same book.

The second adjustment is becoming comfortable with your own order visibility. Because limits orders are posted publicly, other traders can see your intentions. This sounds disadvantageous, but it reverses an asymmetry that favors market makers on centralized exchanges. On a CEX, market makers see your order and can adjust their quotes before you fill. On Hyperliquid, if a market maker moves quotes after you post a limit order, they are moving the market publicly, and you can respond. The psychology shifts from “my order is hidden until I hit execute” to “my order is part of the market.” Experienced limit-order traders often find this less stressful once they adjust because the market is not secretly moving against them.

The third adjustment is treating zero fees differently. On a centralized exchange, a trader paying 0.05 percent in commissions adds that into the cost of every round trip. On Hyperliquid, the explicit fee cost is zero. Some traders respond by overtrading because they do not feel the friction of commissions. This is a trap. The implicit cost of trading—the spread and slippage from moving the market with your order—still exists. A trader who enters and exits the same position frequently on Hyperliquid pays zero fees but can still lose money to spread and adverse price movement. Transparency and zero fees do not eliminate market economics; they make the remaining economics clearer.

Why institutional traders must rethink strategy on transparent order books

Institutional traders built many profitable strategies on centralized exchange market structures that Hyperliquid does not support. Strategies relying on dark pool order detection, predatory routing around liquidity, or advance knowledge of order flow patterns cannot be replicated on a transparent book. Market makers who profited from information asymmetry face a different competitive environment. This does not mean professional traders cannot profit on Hyperliquid; it means their edge must come from actual execution skill, market insight, and faster reaction times rather than from structural information advantages.

Some institutional traders are adapting by focusing on prediction and market-making across Hyperliquid and other transparent venues. If Ethereum perpetuals are trading at slightly different prices on Hyperliquid versus another DEX, and the gap is larger than the cost of moving capital and executing trades, that becomes a pure arbitrage opportunity visible to anyone watching both books. Sophisticated traders build infrastructure to spot these opportunities faster and execute the trades before they disappear. This is different from the dark pool game, but it rewards speed, capital efficiency, and technical sophistication in the same way.

Another institutional strategy shift involves taking advantage of the zero-fee structure to engage in tighter market-making. On a centralized exchange, a market maker might post spreads of 2 basis points but charge themselves 1 basis point in fees, resulting in net revenue of 1 basis point per round trip. On Hyperliquid, they can post spreads of 1 basis point with zero fees and double their revenue per round trip if volume remains constant. This incentive drives competition and tighter spreads across the board. The traders who benefit most are those willing to use the transparent, low-cost infrastructure to their advantage rather than trying to recreate dark pool dynamics that never existed on-chain.

Market structure evolution and the future of retail access

The longer-term significance of Hyperliquid’s transparent order book is structural. As more trading volume migrates to fully on-chain venues, the advantages of centralized dark pools erode. Market makers and traders have less reason to fragment their liquidity across multiple platforms if one platform offers zero fees, transparent execution, and regulatory clarity. This does not mean centralized exchanges disappear; it means they must compete on different terms. Some will transition to offering onboarding fiat services and simplified custody rather than proprietary trading advantages. Others may attempt to remain opaque, but they will face competition from venues that offer the opposite.

For retail traders, the practical effect is a reduction in structural disadvantage. The information asymmetry that institutional traders and market makers exploited for decades was profitable precisely because retail traders could not see order flow, could not verify execution, and could not compare prices across dark pools. On a transparent book, a retail trader with basic market sense and reasonable execution discipline can avoid the worst outcomes. They cannot beat professional traders consistently, but they can stop being harvested by structural opacity.

The remaining edge belongs to traders who understand market structure and leverage it. This might mean timing orders to coincide with known liquidity events, using limit orders strategically instead of market orders, or building positions across time based on public order book patterns. The transparency advantage is not that anyone can suddenly profit; it is that profit and loss becomes a function of actual trading skill rather than information privilege that cannot be accessed. For traders moving from centralized exchanges to Hyperliquid, that shift alone justifies the adjustment period.

Frequently asked questions

What is a dark pool and why do retail traders lose money in them?

A dark pool is a private trading venue where orders are matched away from the public order book, typically on centralized exchanges. Retail traders do not know whether their orders are being filled in a dark pool or at a worse price than what was available on the lit book. Market makers with information about dark pool flow can adjust public quotes to profit before retail orders reach the visible order book. Hyperliquid eliminates dark pools entirely by making all orders visible on the transparent blockchain.

How does an on-chain order book prevent information asymmetry?

Every order posted to an on-chain order book is immediately visible to all participants. There is no privileged early access and no hidden matching engines. When a trade executes, it is recorded on the blockchain and can be verified by anyone. This means no participant has the advantage of seeing orders before others, and no venue operator can profit by routing orders to themselves or affiliated market makers without everyone seeing it happen.

Can retail traders actually make money on a transparent order book like Hyperliquid?

Yes, but profitability depends on skill rather than information privilege. The transparency eliminates one structural disadvantage retail traders face on centralized exchanges. Retail traders can still lose money through poor timing, overleveraging, or bad market predictions. However, they no longer lose money specifically because their broker hid better prices or routed their order to a dark pool. Success on a transparent book comes from understanding order book dynamics, using limit orders effectively, and managing position sizing—the same factors that separate profitable traders from unprofitable ones everywhere.

Hyperliquid’s Order Book Transparency vs. CEX Dark Pools: Why Real-Time Visibility Changes Trading Strategy

A retail trader places a market order for 10 Bitcoin perpetuals on a centralized exchange. The order is instantly filled, but at a price that moved 15 basis points against them between the moment they clicked submit and execution. They do not know whether that slippage came from market movement, their broker’s routing decision, or a dark pool matching engine designed to extract value from retail flow. On Hyperliquid, the same order would execute against a fully visible on-chain order book where every bid, ask, and pending order is observable in real time by every participant. The execution price is not a surprise; it is a transparent outcome of supply and demand that can be verified before and after settlement.

That structural difference creates a material advantage for traders willing to understand it. Centralized exchanges have long relied on information opacity to manage order flow and optimize routing in their own interests. Their dark pools, internal matching engines, and opaque pricing create a zone where institutional traders with market-making arrangements and technology investments can extract consistent value from retail participants who cannot see what is actually happening underneath the trading interface. Hyperliquid’s hyperliquid-dex.com eliminates that asymmetry by making the order book itself a public resource. Every trader sees the same quotes, the same depth, and the same execution prices. The consequence is not free money. It is a level where skill, speed, and strategy matter more than information privilege.

How dark pools create invisible information asymmetry

A dark pool is a private trading venue operated by a centralized exchange or independent broker where orders are matched away from the public order book. On most major exchanges, a significant percentage of order flow—sometimes 30 to 50 percent—never touches the lit book. A retail trader entering a market order on Binance or Coinbase has no visibility into what portion of their order is being filled in a dark pool, at what price, or whether their flow is being sent to a market maker that benefits from seeing the order first.

The economic logic is straightforward. An exchange or broker operator has a financial incentive to internalize order flow because it creates a spread between what they pay the seller and charge the buyer. If they can match retail buy orders against retail sell orders without posting to a public book, they pocket the difference. If retail flow is imbalanced—more buyers than sellers, for example—they can route that flow to affiliated market makers who will fill it at a price slightly worse than the lit book but better than the retail trader might get elsewhere. The retail trader feels they got filled quickly and at a “reasonable” price. They do not see the alternative execution that was possible or the venue where their order actually settled.

This structure also creates a hidden information advantage. When a market maker on an exchange sees that large buy orders are coming into dark pools, they can adjust their public quotes upward before those buyers reach the lit book. By the time a retail trader’s limit order reaches the public order book, the price has already moved. The trader was outrun by an information signal they could not access. Institutional traders with co-location rights, direct exchange connections, and relationships with market makers benefit from seeing order flow patterns that retail participants cannot. The fee structure reinforces this: some exchanges charge less for high-volume traders or market makers and more for retail, directly subsidizing the information advantage.

Why fully transparent on-chain order books change the execution calculus

An on-chain order book operates on a completely different principle. Every order—bid, ask, cancellation, partial fill—is recorded on the blockchain in a transaction that every node validates and stores. There is no dark pool, no internal matching engine, and no hidden flow. When a trader places a limit order on Hyperliquid, that order becomes visible to all other participants immediately. They can see the exact price, the quantity, and the time it entered the book. When their own market order executes, they can see which orders it filled against and verify the prices on the blockchain itself.

This eliminates the information asymmetry in two ways. First, no participant has privileged early sight of orders. Everyone watching the blockchain sees orders at the same time. A market maker cannot route retail flow to themselves; their quotes are submitted to the same book as everyone else. Second, execution cannot be hidden. The transaction that fills an order is immutable and publicly queryable. A trader can verify the exact price they received and confirm that no better price was available at that moment on the book. There is no “best execution” argument because execution was transparent and deterministic.

The mechanics of this transparency also create behavioral effects. Because every limit order is visible, competitors can see what prices are defended and what gaps exist. This tends to reduce the spreads that market makers can maintain without being filled immediately. Because orders cannot be hidden until the moment of execution, traders cannot use dark pools to mask large positions. A trader building a large position must either move the market with visible orders or split their intentions across time. These are not slight improvements; they are fundamental structural differences that alter the risk-reward of various trading strategies.

Comparing liquidity depth: transparency versus convenience

The question many traders ask is whether a fully transparent, decentralized perpetual exchange can offer the same liquidity depth and spread quality as a centralized platform with years of market-maker relationships and order flow concentration. This is where CEX performance and DEX transparency must be evaluated together rather than treated as mutually exclusive. Hyperliquid has attracted significant liquidity because its transparent order book and zero trading fees eliminate the economic incentive for market makers to fragment their capital across multiple venues. If a market maker can operate on a fully transparent book with no fees and no custodial risk, they can afford to provide deeper quotes than they would on a platform where they compete against dark pools and information asymmetries.

The execution speed on Hyperliquid is designed to match or exceed CEX performance. The platform processes orders with sub-millisecond latency and settles them on-chain without requiring withdrawal or deposit delays between trades. A trader moving from a centralized exchange may initially feel that tighter spreads and faster execution are not guaranteed. However, the structure creates incentives for the opposite. A market maker on a transparent book serves the public at whatever spread they choose; if that spread is too wide, someone else will post a tighter quote. The competitive pressure is immediate and verifiable. On a centralized exchange, a market maker can widen spreads based on internalized order flow patterns that no one else can see.

The practical difference becomes visible during volatility. On a centralized exchange, spreads widen when volume surges because market makers reduce their size and the exchange’s dark pool matching engine can no longer fully hide large orders. On Hyperliquid, spreads can widen, but the widening happens at a single, transparent price level visible to all participants. No trader is surprised by a fill that disappeared into an opaque matching engine. The same market-making physics apply, but the information is distributed equally.

How retail traders can exploit on-chain visibility for execution advantage

The simplest advantage of transparent order book trading is order placement strategy. A retail trader can see exactly where liquidity sits and where gaps exist. If a perpetual contract for Ethereum is trading with $500,000 in bids at $2,350 and $400,000 in asks at $2,351, that trader knows exactly what they are bidding into or offering against. On a centralized exchange, the trader sees the public book but not the dark pool flow that might execute their order at a worse price. On Hyperliquid, what they see is what they get.

This visibility advantage compounds for limit orders. A trader can post a limit order to buy Bitcoin perps at a specific price and know that if their order is filled, it filled against orders actually posted to the visible book. They do not need to worry that their order was filled against a dark pool fill that would not have been available if the venue had been transparent. They also can observe when their orders are filled and by how much, allowing them to refine their pricing strategy in real time. If an order does not fill for several seconds, they can examine the order book and understand why.

For swing traders and position builders, on-chain visibility reveals something critical about order flow patterns. A trader watching the Hyperliquid order book for Bitcoin perpetuals can see when large orders are being accumulated by other participants. If bid-side depth suddenly increases, it suggests either new buyers entering or long positions being accumulated. If that same depth disappears quickly, it suggests positions being liquidated or closed. These are pure signals of market behavior that are valuable for directional decisions. On a centralized exchange, some of that signal is hidden in dark pools or is captured privately by the exchange’s own market makers.

Advanced traders can also use the transparent order book to execute large positions with minimal slippage. Instead of entering a market order that moves the price against them, they can observe the standing liquidity and decide whether to pick off small orders across multiple price levels or split their order across time. The blockchain records every trade, so a sophisticated trader can analyze historical patterns and optimize execution timing. This kind of analysis is available on centralized exchanges too, but on Hyperliquid it is based on transparent ground truth rather than whatever order flow the exchange chose to disclose.

The behavioral shift required to adapt from CEX to decentralized perpetual exchanges

A trader switching from a centralized exchange to a fully transparent decentralized perpetual exchange must adjust several habits. The first adjustment is accepting that the order book is the market, not a representation of it. On a centralized exchange, a trader mentally maps the visible book to some larger true market that includes dark pools. On Hyperliquid, the visible book is the complete market for that instrument. This is simpler in principle but requires a mindset shift. The trader must stop wondering if a better price exists elsewhere and start understanding that if it did, it would be on the same book.

The second adjustment is becoming comfortable with your own order visibility. Because limits orders are posted publicly, other traders can see your intentions. This sounds disadvantageous, but it reverses an asymmetry that favors market makers on centralized exchanges. On a CEX, market makers see your order and can adjust their quotes before you fill. On Hyperliquid, if a market maker moves quotes after you post a limit order, they are moving the market publicly, and you can respond. The psychology shifts from “my order is hidden until I hit execute” to “my order is part of the market.” Experienced limit-order traders often find this less stressful once they adjust because the market is not secretly moving against them.

The third adjustment is treating zero fees differently. On a centralized exchange, a trader paying 0.05 percent in commissions adds that into the cost of every round trip. On Hyperliquid, the explicit fee cost is zero. Some traders respond by overtrading because they do not feel the friction of commissions. This is a trap. The implicit cost of trading—the spread and slippage from moving the market with your order—still exists. A trader who enters and exits the same position frequently on Hyperliquid pays zero fees but can still lose money to spread and adverse price movement. Transparency and zero fees do not eliminate market economics; they make the remaining economics clearer.

Why institutional traders must rethink strategy on transparent order books

Institutional traders built many profitable strategies on centralized exchange market structures that Hyperliquid does not support. Strategies relying on dark pool order detection, predatory routing around liquidity, or advance knowledge of order flow patterns cannot be replicated on a transparent book. Market makers who profited from information asymmetry face a different competitive environment. This does not mean professional traders cannot profit on Hyperliquid; it means their edge must come from actual execution skill, market insight, and faster reaction times rather than from structural information advantages.

Some institutional traders are adapting by focusing on prediction and market-making across Hyperliquid and other transparent venues. If Ethereum perpetuals are trading at slightly different prices on Hyperliquid versus another DEX, and the gap is larger than the cost of moving capital and executing trades, that becomes a pure arbitrage opportunity visible to anyone watching both books. Sophisticated traders build infrastructure to spot these opportunities faster and execute the trades before they disappear. This is different from the dark pool game, but it rewards speed, capital efficiency, and technical sophistication in the same way.

Another institutional strategy shift involves taking advantage of the zero-fee structure to engage in tighter market-making. On a centralized exchange, a market maker might post spreads of 2 basis points but charge themselves 1 basis point in fees, resulting in net revenue of 1 basis point per round trip. On Hyperliquid, they can post spreads of 1 basis point with zero fees and double their revenue per round trip if volume remains constant. This incentive drives competition and tighter spreads across the board. The traders who benefit most are those willing to use the transparent, low-cost infrastructure to their advantage rather than trying to recreate dark pool dynamics that never existed on-chain.

Market structure evolution and the future of retail access

The longer-term significance of Hyperliquid’s transparent order book is structural. As more trading volume migrates to fully on-chain venues, the advantages of centralized dark pools erode. Market makers and traders have less reason to fragment their liquidity across multiple platforms if one platform offers zero fees, transparent execution, and regulatory clarity. This does not mean centralized exchanges disappear; it means they must compete on different terms. Some will transition to offering onboarding fiat services and simplified custody rather than proprietary trading advantages. Others may attempt to remain opaque, but they will face competition from venues that offer the opposite.

For retail traders, the practical effect is a reduction in structural disadvantage. The information asymmetry that institutional traders and market makers exploited for decades was profitable precisely because retail traders could not see order flow, could not verify execution, and could not compare prices across dark pools. On a transparent book, a retail trader with basic market sense and reasonable execution discipline can avoid the worst outcomes. They cannot beat professional traders consistently, but they can stop being harvested by structural opacity.

The remaining edge belongs to traders who understand market structure and leverage it. This might mean timing orders to coincide with known liquidity events, using limit orders strategically instead of market orders, or building positions across time based on public order book patterns. The transparency advantage is not that anyone can suddenly profit; it is that profit and loss becomes a function of actual trading skill rather than information privilege that cannot be accessed. For traders moving from centralized exchanges to Hyperliquid, that shift alone justifies the adjustment period.

Frequently asked questions

What is a dark pool and why do retail traders lose money in them?

A dark pool is a private trading venue where orders are matched away from the public order book, typically on centralized exchanges. Retail traders do not know whether their orders are being filled in a dark pool or at a worse price than what was available on the lit book. Market makers with information about dark pool flow can adjust public quotes to profit before retail orders reach the visible order book. Hyperliquid eliminates dark pools entirely by making all orders visible on the transparent blockchain.

How does an on-chain order book prevent information asymmetry?

Every order posted to an on-chain order book is immediately visible to all participants. There is no privileged early access and no hidden matching engines. When a trade executes, it is recorded on the blockchain and can be verified by anyone. This means no participant has the advantage of seeing orders before others, and no venue operator can profit by routing orders to themselves or affiliated market makers without everyone seeing it happen.

Can retail traders actually make money on a transparent order book like Hyperliquid?

Yes, but profitability depends on skill rather than information privilege. The transparency eliminates one structural disadvantage retail traders face on centralized exchanges. Retail traders can still lose money through poor timing, overleveraging, or bad market predictions. However, they no longer lose money specifically because their broker hid better prices or routed their order to a dark pool. Success on a transparent book comes from understanding order book dynamics, using limit orders effectively, and managing position sizing—the same factors that separate profitable traders from unprofitable ones everywhere.

Hyperliquid’s Order Book Transparency vs. CEX Dark Pools: Why Real-Time Visibility Changes Trading Strategy

A retail trader places a market order for 10 Bitcoin perpetuals on a centralized exchange. The order is instantly filled, but at a price that moved 15 basis points against them between the moment they clicked submit and execution. They do not know whether that slippage came from market movement, their broker’s routing decision, or a dark pool matching engine designed to extract value from retail flow. On Hyperliquid, the same order would execute against a fully visible on-chain order book where every bid, ask, and pending order is observable in real time by every participant. The execution price is not a surprise; it is a transparent outcome of supply and demand that can be verified before and after settlement.

That structural difference creates a material advantage for traders willing to understand it. Centralized exchanges have long relied on information opacity to manage order flow and optimize routing in their own interests. Their dark pools, internal matching engines, and opaque pricing create a zone where institutional traders with market-making arrangements and technology investments can extract consistent value from retail participants who cannot see what is actually happening underneath the trading interface. Hyperliquid’s hyperliquid-dex.com eliminates that asymmetry by making the order book itself a public resource. Every trader sees the same quotes, the same depth, and the same execution prices. The consequence is not free money. It is a level where skill, speed, and strategy matter more than information privilege.

How dark pools create invisible information asymmetry

A dark pool is a private trading venue operated by a centralized exchange or independent broker where orders are matched away from the public order book. On most major exchanges, a significant percentage of order flow—sometimes 30 to 50 percent—never touches the lit book. A retail trader entering a market order on Binance or Coinbase has no visibility into what portion of their order is being filled in a dark pool, at what price, or whether their flow is being sent to a market maker that benefits from seeing the order first.

The economic logic is straightforward. An exchange or broker operator has a financial incentive to internalize order flow because it creates a spread between what they pay the seller and charge the buyer. If they can match retail buy orders against retail sell orders without posting to a public book, they pocket the difference. If retail flow is imbalanced—more buyers than sellers, for example—they can route that flow to affiliated market makers who will fill it at a price slightly worse than the lit book but better than the retail trader might get elsewhere. The retail trader feels they got filled quickly and at a “reasonable” price. They do not see the alternative execution that was possible or the venue where their order actually settled.

This structure also creates a hidden information advantage. When a market maker on an exchange sees that large buy orders are coming into dark pools, they can adjust their public quotes upward before those buyers reach the lit book. By the time a retail trader’s limit order reaches the public order book, the price has already moved. The trader was outrun by an information signal they could not access. Institutional traders with co-location rights, direct exchange connections, and relationships with market makers benefit from seeing order flow patterns that retail participants cannot. The fee structure reinforces this: some exchanges charge less for high-volume traders or market makers and more for retail, directly subsidizing the information advantage.

Why fully transparent on-chain order books change the execution calculus

An on-chain order book operates on a completely different principle. Every order—bid, ask, cancellation, partial fill—is recorded on the blockchain in a transaction that every node validates and stores. There is no dark pool, no internal matching engine, and no hidden flow. When a trader places a limit order on Hyperliquid, that order becomes visible to all other participants immediately. They can see the exact price, the quantity, and the time it entered the book. When their own market order executes, they can see which orders it filled against and verify the prices on the blockchain itself.

This eliminates the information asymmetry in two ways. First, no participant has privileged early sight of orders. Everyone watching the blockchain sees orders at the same time. A market maker cannot route retail flow to themselves; their quotes are submitted to the same book as everyone else. Second, execution cannot be hidden. The transaction that fills an order is immutable and publicly queryable. A trader can verify the exact price they received and confirm that no better price was available at that moment on the book. There is no “best execution” argument because execution was transparent and deterministic.

The mechanics of this transparency also create behavioral effects. Because every limit order is visible, competitors can see what prices are defended and what gaps exist. This tends to reduce the spreads that market makers can maintain without being filled immediately. Because orders cannot be hidden until the moment of execution, traders cannot use dark pools to mask large positions. A trader building a large position must either move the market with visible orders or split their intentions across time. These are not slight improvements; they are fundamental structural differences that alter the risk-reward of various trading strategies.

Comparing liquidity depth: transparency versus convenience

The question many traders ask is whether a fully transparent, decentralized perpetual exchange can offer the same liquidity depth and spread quality as a centralized platform with years of market-maker relationships and order flow concentration. This is where CEX performance and DEX transparency must be evaluated together rather than treated as mutually exclusive. Hyperliquid has attracted significant liquidity because its transparent order book and zero trading fees eliminate the economic incentive for market makers to fragment their capital across multiple venues. If a market maker can operate on a fully transparent book with no fees and no custodial risk, they can afford to provide deeper quotes than they would on a platform where they compete against dark pools and information asymmetries.

The execution speed on Hyperliquid is designed to match or exceed CEX performance. The platform processes orders with sub-millisecond latency and settles them on-chain without requiring withdrawal or deposit delays between trades. A trader moving from a centralized exchange may initially feel that tighter spreads and faster execution are not guaranteed. However, the structure creates incentives for the opposite. A market maker on a transparent book serves the public at whatever spread they choose; if that spread is too wide, someone else will post a tighter quote. The competitive pressure is immediate and verifiable. On a centralized exchange, a market maker can widen spreads based on internalized order flow patterns that no one else can see.

The practical difference becomes visible during volatility. On a centralized exchange, spreads widen when volume surges because market makers reduce their size and the exchange’s dark pool matching engine can no longer fully hide large orders. On Hyperliquid, spreads can widen, but the widening happens at a single, transparent price level visible to all participants. No trader is surprised by a fill that disappeared into an opaque matching engine. The same market-making physics apply, but the information is distributed equally.

How retail traders can exploit on-chain visibility for execution advantage

The simplest advantage of transparent order book trading is order placement strategy. A retail trader can see exactly where liquidity sits and where gaps exist. If a perpetual contract for Ethereum is trading with $500,000 in bids at $2,350 and $400,000 in asks at $2,351, that trader knows exactly what they are bidding into or offering against. On a centralized exchange, the trader sees the public book but not the dark pool flow that might execute their order at a worse price. On Hyperliquid, what they see is what they get.

This visibility advantage compounds for limit orders. A trader can post a limit order to buy Bitcoin perps at a specific price and know that if their order is filled, it filled against orders actually posted to the visible book. They do not need to worry that their order was filled against a dark pool fill that would not have been available if the venue had been transparent. They also can observe when their orders are filled and by how much, allowing them to refine their pricing strategy in real time. If an order does not fill for several seconds, they can examine the order book and understand why.

For swing traders and position builders, on-chain visibility reveals something critical about order flow patterns. A trader watching the Hyperliquid order book for Bitcoin perpetuals can see when large orders are being accumulated by other participants. If bid-side depth suddenly increases, it suggests either new buyers entering or long positions being accumulated. If that same depth disappears quickly, it suggests positions being liquidated or closed. These are pure signals of market behavior that are valuable for directional decisions. On a centralized exchange, some of that signal is hidden in dark pools or is captured privately by the exchange’s own market makers.

Advanced traders can also use the transparent order book to execute large positions with minimal slippage. Instead of entering a market order that moves the price against them, they can observe the standing liquidity and decide whether to pick off small orders across multiple price levels or split their order across time. The blockchain records every trade, so a sophisticated trader can analyze historical patterns and optimize execution timing. This kind of analysis is available on centralized exchanges too, but on Hyperliquid it is based on transparent ground truth rather than whatever order flow the exchange chose to disclose.

The behavioral shift required to adapt from CEX to decentralized perpetual exchanges

A trader switching from a centralized exchange to a fully transparent decentralized perpetual exchange must adjust several habits. The first adjustment is accepting that the order book is the market, not a representation of it. On a centralized exchange, a trader mentally maps the visible book to some larger true market that includes dark pools. On Hyperliquid, the visible book is the complete market for that instrument. This is simpler in principle but requires a mindset shift. The trader must stop wondering if a better price exists elsewhere and start understanding that if it did, it would be on the same book.

The second adjustment is becoming comfortable with your own order visibility. Because limits orders are posted publicly, other traders can see your intentions. This sounds disadvantageous, but it reverses an asymmetry that favors market makers on centralized exchanges. On a CEX, market makers see your order and can adjust their quotes before you fill. On Hyperliquid, if a market maker moves quotes after you post a limit order, they are moving the market publicly, and you can respond. The psychology shifts from “my order is hidden until I hit execute” to “my order is part of the market.” Experienced limit-order traders often find this less stressful once they adjust because the market is not secretly moving against them.

The third adjustment is treating zero fees differently. On a centralized exchange, a trader paying 0.05 percent in commissions adds that into the cost of every round trip. On Hyperliquid, the explicit fee cost is zero. Some traders respond by overtrading because they do not feel the friction of commissions. This is a trap. The implicit cost of trading—the spread and slippage from moving the market with your order—still exists. A trader who enters and exits the same position frequently on Hyperliquid pays zero fees but can still lose money to spread and adverse price movement. Transparency and zero fees do not eliminate market economics; they make the remaining economics clearer.

Why institutional traders must rethink strategy on transparent order books

Institutional traders built many profitable strategies on centralized exchange market structures that Hyperliquid does not support. Strategies relying on dark pool order detection, predatory routing around liquidity, or advance knowledge of order flow patterns cannot be replicated on a transparent book. Market makers who profited from information asymmetry face a different competitive environment. This does not mean professional traders cannot profit on Hyperliquid; it means their edge must come from actual execution skill, market insight, and faster reaction times rather than from structural information advantages.

Some institutional traders are adapting by focusing on prediction and market-making across Hyperliquid and other transparent venues. If Ethereum perpetuals are trading at slightly different prices on Hyperliquid versus another DEX, and the gap is larger than the cost of moving capital and executing trades, that becomes a pure arbitrage opportunity visible to anyone watching both books. Sophisticated traders build infrastructure to spot these opportunities faster and execute the trades before they disappear. This is different from the dark pool game, but it rewards speed, capital efficiency, and technical sophistication in the same way.

Another institutional strategy shift involves taking advantage of the zero-fee structure to engage in tighter market-making. On a centralized exchange, a market maker might post spreads of 2 basis points but charge themselves 1 basis point in fees, resulting in net revenue of 1 basis point per round trip. On Hyperliquid, they can post spreads of 1 basis point with zero fees and double their revenue per round trip if volume remains constant. This incentive drives competition and tighter spreads across the board. The traders who benefit most are those willing to use the transparent, low-cost infrastructure to their advantage rather than trying to recreate dark pool dynamics that never existed on-chain.

Market structure evolution and the future of retail access

The longer-term significance of Hyperliquid’s transparent order book is structural. As more trading volume migrates to fully on-chain venues, the advantages of centralized dark pools erode. Market makers and traders have less reason to fragment their liquidity across multiple platforms if one platform offers zero fees, transparent execution, and regulatory clarity. This does not mean centralized exchanges disappear; it means they must compete on different terms. Some will transition to offering onboarding fiat services and simplified custody rather than proprietary trading advantages. Others may attempt to remain opaque, but they will face competition from venues that offer the opposite.

For retail traders, the practical effect is a reduction in structural disadvantage. The information asymmetry that institutional traders and market makers exploited for decades was profitable precisely because retail traders could not see order flow, could not verify execution, and could not compare prices across dark pools. On a transparent book, a retail trader with basic market sense and reasonable execution discipline can avoid the worst outcomes. They cannot beat professional traders consistently, but they can stop being harvested by structural opacity.

The remaining edge belongs to traders who understand market structure and leverage it. This might mean timing orders to coincide with known liquidity events, using limit orders strategically instead of market orders, or building positions across time based on public order book patterns. The transparency advantage is not that anyone can suddenly profit; it is that profit and loss becomes a function of actual trading skill rather than information privilege that cannot be accessed. For traders moving from centralized exchanges to Hyperliquid, that shift alone justifies the adjustment period.

Frequently asked questions

What is a dark pool and why do retail traders lose money in them?

A dark pool is a private trading venue where orders are matched away from the public order book, typically on centralized exchanges. Retail traders do not know whether their orders are being filled in a dark pool or at a worse price than what was available on the lit book. Market makers with information about dark pool flow can adjust public quotes to profit before retail orders reach the visible order book. Hyperliquid eliminates dark pools entirely by making all orders visible on the transparent blockchain.

How does an on-chain order book prevent information asymmetry?

Every order posted to an on-chain order book is immediately visible to all participants. There is no privileged early access and no hidden matching engines. When a trade executes, it is recorded on the blockchain and can be verified by anyone. This means no participant has the advantage of seeing orders before others, and no venue operator can profit by routing orders to themselves or affiliated market makers without everyone seeing it happen.

Can retail traders actually make money on a transparent order book like Hyperliquid?

Yes, but profitability depends on skill rather than information privilege. The transparency eliminates one structural disadvantage retail traders face on centralized exchanges. Retail traders can still lose money through poor timing, overleveraging, or bad market predictions. However, they no longer lose money specifically because their broker hid better prices or routed their order to a dark pool. Success on a transparent book comes from understanding order book dynamics, using limit orders effectively, and managing position sizing—the same factors that separate profitable traders from unprofitable ones everywhere.

Hyperliquid’s Order Book Transparency vs. CEX Dark Pools: Why Real-Time Visibility Changes Trading Strategy

A retail trader places a market order for 10 Bitcoin perpetuals on a centralized exchange. The order is instantly filled, but at a price that moved 15 basis points against them between the moment they clicked submit and execution. They do not know whether that slippage came from market movement, their broker’s routing decision, or a dark pool matching engine designed to extract value from retail flow. On Hyperliquid, the same order would execute against a fully visible on-chain order book where every bid, ask, and pending order is observable in real time by every participant. The execution price is not a surprise; it is a transparent outcome of supply and demand that can be verified before and after settlement.

That structural difference creates a material advantage for traders willing to understand it. Centralized exchanges have long relied on information opacity to manage order flow and optimize routing in their own interests. Their dark pools, internal matching engines, and opaque pricing create a zone where institutional traders with market-making arrangements and technology investments can extract consistent value from retail participants who cannot see what is actually happening underneath the trading interface. Hyperliquid’s hyperliquid-dex.com eliminates that asymmetry by making the order book itself a public resource. Every trader sees the same quotes, the same depth, and the same execution prices. The consequence is not free money. It is a level where skill, speed, and strategy matter more than information privilege.

How dark pools create invisible information asymmetry

A dark pool is a private trading venue operated by a centralized exchange or independent broker where orders are matched away from the public order book. On most major exchanges, a significant percentage of order flow—sometimes 30 to 50 percent—never touches the lit book. A retail trader entering a market order on Binance or Coinbase has no visibility into what portion of their order is being filled in a dark pool, at what price, or whether their flow is being sent to a market maker that benefits from seeing the order first.

The economic logic is straightforward. An exchange or broker operator has a financial incentive to internalize order flow because it creates a spread between what they pay the seller and charge the buyer. If they can match retail buy orders against retail sell orders without posting to a public book, they pocket the difference. If retail flow is imbalanced—more buyers than sellers, for example—they can route that flow to affiliated market makers who will fill it at a price slightly worse than the lit book but better than the retail trader might get elsewhere. The retail trader feels they got filled quickly and at a “reasonable” price. They do not see the alternative execution that was possible or the venue where their order actually settled.

This structure also creates a hidden information advantage. When a market maker on an exchange sees that large buy orders are coming into dark pools, they can adjust their public quotes upward before those buyers reach the lit book. By the time a retail trader’s limit order reaches the public order book, the price has already moved. The trader was outrun by an information signal they could not access. Institutional traders with co-location rights, direct exchange connections, and relationships with market makers benefit from seeing order flow patterns that retail participants cannot. The fee structure reinforces this: some exchanges charge less for high-volume traders or market makers and more for retail, directly subsidizing the information advantage.

Why fully transparent on-chain order books change the execution calculus

An on-chain order book operates on a completely different principle. Every order—bid, ask, cancellation, partial fill—is recorded on the blockchain in a transaction that every node validates and stores. There is no dark pool, no internal matching engine, and no hidden flow. When a trader places a limit order on Hyperliquid, that order becomes visible to all other participants immediately. They can see the exact price, the quantity, and the time it entered the book. When their own market order executes, they can see which orders it filled against and verify the prices on the blockchain itself.

This eliminates the information asymmetry in two ways. First, no participant has privileged early sight of orders. Everyone watching the blockchain sees orders at the same time. A market maker cannot route retail flow to themselves; their quotes are submitted to the same book as everyone else. Second, execution cannot be hidden. The transaction that fills an order is immutable and publicly queryable. A trader can verify the exact price they received and confirm that no better price was available at that moment on the book. There is no “best execution” argument because execution was transparent and deterministic.

The mechanics of this transparency also create behavioral effects. Because every limit order is visible, competitors can see what prices are defended and what gaps exist. This tends to reduce the spreads that market makers can maintain without being filled immediately. Because orders cannot be hidden until the moment of execution, traders cannot use dark pools to mask large positions. A trader building a large position must either move the market with visible orders or split their intentions across time. These are not slight improvements; they are fundamental structural differences that alter the risk-reward of various trading strategies.

Comparing liquidity depth: transparency versus convenience

The question many traders ask is whether a fully transparent, decentralized perpetual exchange can offer the same liquidity depth and spread quality as a centralized platform with years of market-maker relationships and order flow concentration. This is where CEX performance and DEX transparency must be evaluated together rather than treated as mutually exclusive. Hyperliquid has attracted significant liquidity because its transparent order book and zero trading fees eliminate the economic incentive for market makers to fragment their capital across multiple venues. If a market maker can operate on a fully transparent book with no fees and no custodial risk, they can afford to provide deeper quotes than they would on a platform where they compete against dark pools and information asymmetries.

The execution speed on Hyperliquid is designed to match or exceed CEX performance. The platform processes orders with sub-millisecond latency and settles them on-chain without requiring withdrawal or deposit delays between trades. A trader moving from a centralized exchange may initially feel that tighter spreads and faster execution are not guaranteed. However, the structure creates incentives for the opposite. A market maker on a transparent book serves the public at whatever spread they choose; if that spread is too wide, someone else will post a tighter quote. The competitive pressure is immediate and verifiable. On a centralized exchange, a market maker can widen spreads based on internalized order flow patterns that no one else can see.

The practical difference becomes visible during volatility. On a centralized exchange, spreads widen when volume surges because market makers reduce their size and the exchange’s dark pool matching engine can no longer fully hide large orders. On Hyperliquid, spreads can widen, but the widening happens at a single, transparent price level visible to all participants. No trader is surprised by a fill that disappeared into an opaque matching engine. The same market-making physics apply, but the information is distributed equally.

How retail traders can exploit on-chain visibility for execution advantage

The simplest advantage of transparent order book trading is order placement strategy. A retail trader can see exactly where liquidity sits and where gaps exist. If a perpetual contract for Ethereum is trading with $500,000 in bids at $2,350 and $400,000 in asks at $2,351, that trader knows exactly what they are bidding into or offering against. On a centralized exchange, the trader sees the public book but not the dark pool flow that might execute their order at a worse price. On Hyperliquid, what they see is what they get.

This visibility advantage compounds for limit orders. A trader can post a limit order to buy Bitcoin perps at a specific price and know that if their order is filled, it filled against orders actually posted to the visible book. They do not need to worry that their order was filled against a dark pool fill that would not have been available if the venue had been transparent. They also can observe when their orders are filled and by how much, allowing them to refine their pricing strategy in real time. If an order does not fill for several seconds, they can examine the order book and understand why.

For swing traders and position builders, on-chain visibility reveals something critical about order flow patterns. A trader watching the Hyperliquid order book for Bitcoin perpetuals can see when large orders are being accumulated by other participants. If bid-side depth suddenly increases, it suggests either new buyers entering or long positions being accumulated. If that same depth disappears quickly, it suggests positions being liquidated or closed. These are pure signals of market behavior that are valuable for directional decisions. On a centralized exchange, some of that signal is hidden in dark pools or is captured privately by the exchange’s own market makers.

Advanced traders can also use the transparent order book to execute large positions with minimal slippage. Instead of entering a market order that moves the price against them, they can observe the standing liquidity and decide whether to pick off small orders across multiple price levels or split their order across time. The blockchain records every trade, so a sophisticated trader can analyze historical patterns and optimize execution timing. This kind of analysis is available on centralized exchanges too, but on Hyperliquid it is based on transparent ground truth rather than whatever order flow the exchange chose to disclose.

The behavioral shift required to adapt from CEX to decentralized perpetual exchanges

A trader switching from a centralized exchange to a fully transparent decentralized perpetual exchange must adjust several habits. The first adjustment is accepting that the order book is the market, not a representation of it. On a centralized exchange, a trader mentally maps the visible book to some larger true market that includes dark pools. On Hyperliquid, the visible book is the complete market for that instrument. This is simpler in principle but requires a mindset shift. The trader must stop wondering if a better price exists elsewhere and start understanding that if it did, it would be on the same book.

The second adjustment is becoming comfortable with your own order visibility. Because limits orders are posted publicly, other traders can see your intentions. This sounds disadvantageous, but it reverses an asymmetry that favors market makers on centralized exchanges. On a CEX, market makers see your order and can adjust their quotes before you fill. On Hyperliquid, if a market maker moves quotes after you post a limit order, they are moving the market publicly, and you can respond. The psychology shifts from “my order is hidden until I hit execute” to “my order is part of the market.” Experienced limit-order traders often find this less stressful once they adjust because the market is not secretly moving against them.

The third adjustment is treating zero fees differently. On a centralized exchange, a trader paying 0.05 percent in commissions adds that into the cost of every round trip. On Hyperliquid, the explicit fee cost is zero. Some traders respond by overtrading because they do not feel the friction of commissions. This is a trap. The implicit cost of trading—the spread and slippage from moving the market with your order—still exists. A trader who enters and exits the same position frequently on Hyperliquid pays zero fees but can still lose money to spread and adverse price movement. Transparency and zero fees do not eliminate market economics; they make the remaining economics clearer.

Why institutional traders must rethink strategy on transparent order books

Institutional traders built many profitable strategies on centralized exchange market structures that Hyperliquid does not support. Strategies relying on dark pool order detection, predatory routing around liquidity, or advance knowledge of order flow patterns cannot be replicated on a transparent book. Market makers who profited from information asymmetry face a different competitive environment. This does not mean professional traders cannot profit on Hyperliquid; it means their edge must come from actual execution skill, market insight, and faster reaction times rather than from structural information advantages.

Some institutional traders are adapting by focusing on prediction and market-making across Hyperliquid and other transparent venues. If Ethereum perpetuals are trading at slightly different prices on Hyperliquid versus another DEX, and the gap is larger than the cost of moving capital and executing trades, that becomes a pure arbitrage opportunity visible to anyone watching both books. Sophisticated traders build infrastructure to spot these opportunities faster and execute the trades before they disappear. This is different from the dark pool game, but it rewards speed, capital efficiency, and technical sophistication in the same way.

Another institutional strategy shift involves taking advantage of the zero-fee structure to engage in tighter market-making. On a centralized exchange, a market maker might post spreads of 2 basis points but charge themselves 1 basis point in fees, resulting in net revenue of 1 basis point per round trip. On Hyperliquid, they can post spreads of 1 basis point with zero fees and double their revenue per round trip if volume remains constant. This incentive drives competition and tighter spreads across the board. The traders who benefit most are those willing to use the transparent, low-cost infrastructure to their advantage rather than trying to recreate dark pool dynamics that never existed on-chain.

Market structure evolution and the future of retail access

The longer-term significance of Hyperliquid’s transparent order book is structural. As more trading volume migrates to fully on-chain venues, the advantages of centralized dark pools erode. Market makers and traders have less reason to fragment their liquidity across multiple platforms if one platform offers zero fees, transparent execution, and regulatory clarity. This does not mean centralized exchanges disappear; it means they must compete on different terms. Some will transition to offering onboarding fiat services and simplified custody rather than proprietary trading advantages. Others may attempt to remain opaque, but they will face competition from venues that offer the opposite.

For retail traders, the practical effect is a reduction in structural disadvantage. The information asymmetry that institutional traders and market makers exploited for decades was profitable precisely because retail traders could not see order flow, could not verify execution, and could not compare prices across dark pools. On a transparent book, a retail trader with basic market sense and reasonable execution discipline can avoid the worst outcomes. They cannot beat professional traders consistently, but they can stop being harvested by structural opacity.

The remaining edge belongs to traders who understand market structure and leverage it. This might mean timing orders to coincide with known liquidity events, using limit orders strategically instead of market orders, or building positions across time based on public order book patterns. The transparency advantage is not that anyone can suddenly profit; it is that profit and loss becomes a function of actual trading skill rather than information privilege that cannot be accessed. For traders moving from centralized exchanges to Hyperliquid, that shift alone justifies the adjustment period.

Frequently asked questions

What is a dark pool and why do retail traders lose money in them?

A dark pool is a private trading venue where orders are matched away from the public order book, typically on centralized exchanges. Retail traders do not know whether their orders are being filled in a dark pool or at a worse price than what was available on the lit book. Market makers with information about dark pool flow can adjust public quotes to profit before retail orders reach the visible order book. Hyperliquid eliminates dark pools entirely by making all orders visible on the transparent blockchain.

How does an on-chain order book prevent information asymmetry?

Every order posted to an on-chain order book is immediately visible to all participants. There is no privileged early access and no hidden matching engines. When a trade executes, it is recorded on the blockchain and can be verified by anyone. This means no participant has the advantage of seeing orders before others, and no venue operator can profit by routing orders to themselves or affiliated market makers without everyone seeing it happen.

Can retail traders actually make money on a transparent order book like Hyperliquid?

Yes, but profitability depends on skill rather than information privilege. The transparency eliminates one structural disadvantage retail traders face on centralized exchanges. Retail traders can still lose money through poor timing, overleveraging, or bad market predictions. However, they no longer lose money specifically because their broker hid better prices or routed their order to a dark pool. Success on a transparent book comes from understanding order book dynamics, using limit orders effectively, and managing position sizing—the same factors that separate profitable traders from unprofitable ones everywhere.

Hyperliquid’s Order Book Transparency vs. CEX Dark Pools: Why Real-Time Visibility Changes Trading Strategy

A retail trader places a market order for 10 Bitcoin perpetuals on a centralized exchange. The order is instantly filled, but at a price that moved 15 basis points against them between the moment they clicked submit and execution. They do not know whether that slippage came from market movement, their broker’s routing decision, or a dark pool matching engine designed to extract value from retail flow. On Hyperliquid, the same order would execute against a fully visible on-chain order book where every bid, ask, and pending order is observable in real time by every participant. The execution price is not a surprise; it is a transparent outcome of supply and demand that can be verified before and after settlement.

That structural difference creates a material advantage for traders willing to understand it. Centralized exchanges have long relied on information opacity to manage order flow and optimize routing in their own interests. Their dark pools, internal matching engines, and opaque pricing create a zone where institutional traders with market-making arrangements and technology investments can extract consistent value from retail participants who cannot see what is actually happening underneath the trading interface. Hyperliquid’s hyperliquid-dex.com eliminates that asymmetry by making the order book itself a public resource. Every trader sees the same quotes, the same depth, and the same execution prices. The consequence is not free money. It is a level where skill, speed, and strategy matter more than information privilege.

How dark pools create invisible information asymmetry

A dark pool is a private trading venue operated by a centralized exchange or independent broker where orders are matched away from the public order book. On most major exchanges, a significant percentage of order flow—sometimes 30 to 50 percent—never touches the lit book. A retail trader entering a market order on Binance or Coinbase has no visibility into what portion of their order is being filled in a dark pool, at what price, or whether their flow is being sent to a market maker that benefits from seeing the order first.

The economic logic is straightforward. An exchange or broker operator has a financial incentive to internalize order flow because it creates a spread between what they pay the seller and charge the buyer. If they can match retail buy orders against retail sell orders without posting to a public book, they pocket the difference. If retail flow is imbalanced—more buyers than sellers, for example—they can route that flow to affiliated market makers who will fill it at a price slightly worse than the lit book but better than the retail trader might get elsewhere. The retail trader feels they got filled quickly and at a “reasonable” price. They do not see the alternative execution that was possible or the venue where their order actually settled.

This structure also creates a hidden information advantage. When a market maker on an exchange sees that large buy orders are coming into dark pools, they can adjust their public quotes upward before those buyers reach the lit book. By the time a retail trader’s limit order reaches the public order book, the price has already moved. The trader was outrun by an information signal they could not access. Institutional traders with co-location rights, direct exchange connections, and relationships with market makers benefit from seeing order flow patterns that retail participants cannot. The fee structure reinforces this: some exchanges charge less for high-volume traders or market makers and more for retail, directly subsidizing the information advantage.

Why fully transparent on-chain order books change the execution calculus

An on-chain order book operates on a completely different principle. Every order—bid, ask, cancellation, partial fill—is recorded on the blockchain in a transaction that every node validates and stores. There is no dark pool, no internal matching engine, and no hidden flow. When a trader places a limit order on Hyperliquid, that order becomes visible to all other participants immediately. They can see the exact price, the quantity, and the time it entered the book. When their own market order executes, they can see which orders it filled against and verify the prices on the blockchain itself.

This eliminates the information asymmetry in two ways. First, no participant has privileged early sight of orders. Everyone watching the blockchain sees orders at the same time. A market maker cannot route retail flow to themselves; their quotes are submitted to the same book as everyone else. Second, execution cannot be hidden. The transaction that fills an order is immutable and publicly queryable. A trader can verify the exact price they received and confirm that no better price was available at that moment on the book. There is no “best execution” argument because execution was transparent and deterministic.

The mechanics of this transparency also create behavioral effects. Because every limit order is visible, competitors can see what prices are defended and what gaps exist. This tends to reduce the spreads that market makers can maintain without being filled immediately. Because orders cannot be hidden until the moment of execution, traders cannot use dark pools to mask large positions. A trader building a large position must either move the market with visible orders or split their intentions across time. These are not slight improvements; they are fundamental structural differences that alter the risk-reward of various trading strategies.

Comparing liquidity depth: transparency versus convenience

The question many traders ask is whether a fully transparent, decentralized perpetual exchange can offer the same liquidity depth and spread quality as a centralized platform with years of market-maker relationships and order flow concentration. This is where CEX performance and DEX transparency must be evaluated together rather than treated as mutually exclusive. Hyperliquid has attracted significant liquidity because its transparent order book and zero trading fees eliminate the economic incentive for market makers to fragment their capital across multiple venues. If a market maker can operate on a fully transparent book with no fees and no custodial risk, they can afford to provide deeper quotes than they would on a platform where they compete against dark pools and information asymmetries.

The execution speed on Hyperliquid is designed to match or exceed CEX performance. The platform processes orders with sub-millisecond latency and settles them on-chain without requiring withdrawal or deposit delays between trades. A trader moving from a centralized exchange may initially feel that tighter spreads and faster execution are not guaranteed. However, the structure creates incentives for the opposite. A market maker on a transparent book serves the public at whatever spread they choose; if that spread is too wide, someone else will post a tighter quote. The competitive pressure is immediate and verifiable. On a centralized exchange, a market maker can widen spreads based on internalized order flow patterns that no one else can see.

The practical difference becomes visible during volatility. On a centralized exchange, spreads widen when volume surges because market makers reduce their size and the exchange’s dark pool matching engine can no longer fully hide large orders. On Hyperliquid, spreads can widen, but the widening happens at a single, transparent price level visible to all participants. No trader is surprised by a fill that disappeared into an opaque matching engine. The same market-making physics apply, but the information is distributed equally.

How retail traders can exploit on-chain visibility for execution advantage

The simplest advantage of transparent order book trading is order placement strategy. A retail trader can see exactly where liquidity sits and where gaps exist. If a perpetual contract for Ethereum is trading with $500,000 in bids at $2,350 and $400,000 in asks at $2,351, that trader knows exactly what they are bidding into or offering against. On a centralized exchange, the trader sees the public book but not the dark pool flow that might execute their order at a worse price. On Hyperliquid, what they see is what they get.

This visibility advantage compounds for limit orders. A trader can post a limit order to buy Bitcoin perps at a specific price and know that if their order is filled, it filled against orders actually posted to the visible book. They do not need to worry that their order was filled against a dark pool fill that would not have been available if the venue had been transparent. They also can observe when their orders are filled and by how much, allowing them to refine their pricing strategy in real time. If an order does not fill for several seconds, they can examine the order book and understand why.

For swing traders and position builders, on-chain visibility reveals something critical about order flow patterns. A trader watching the Hyperliquid order book for Bitcoin perpetuals can see when large orders are being accumulated by other participants. If bid-side depth suddenly increases, it suggests either new buyers entering or long positions being accumulated. If that same depth disappears quickly, it suggests positions being liquidated or closed. These are pure signals of market behavior that are valuable for directional decisions. On a centralized exchange, some of that signal is hidden in dark pools or is captured privately by the exchange’s own market makers.

Advanced traders can also use the transparent order book to execute large positions with minimal slippage. Instead of entering a market order that moves the price against them, they can observe the standing liquidity and decide whether to pick off small orders across multiple price levels or split their order across time. The blockchain records every trade, so a sophisticated trader can analyze historical patterns and optimize execution timing. This kind of analysis is available on centralized exchanges too, but on Hyperliquid it is based on transparent ground truth rather than whatever order flow the exchange chose to disclose.

The behavioral shift required to adapt from CEX to decentralized perpetual exchanges

A trader switching from a centralized exchange to a fully transparent decentralized perpetual exchange must adjust several habits. The first adjustment is accepting that the order book is the market, not a representation of it. On a centralized exchange, a trader mentally maps the visible book to some larger true market that includes dark pools. On Hyperliquid, the visible book is the complete market for that instrument. This is simpler in principle but requires a mindset shift. The trader must stop wondering if a better price exists elsewhere and start understanding that if it did, it would be on the same book.

The second adjustment is becoming comfortable with your own order visibility. Because limits orders are posted publicly, other traders can see your intentions. This sounds disadvantageous, but it reverses an asymmetry that favors market makers on centralized exchanges. On a CEX, market makers see your order and can adjust their quotes before you fill. On Hyperliquid, if a market maker moves quotes after you post a limit order, they are moving the market publicly, and you can respond. The psychology shifts from “my order is hidden until I hit execute” to “my order is part of the market.” Experienced limit-order traders often find this less stressful once they adjust because the market is not secretly moving against them.

The third adjustment is treating zero fees differently. On a centralized exchange, a trader paying 0.05 percent in commissions adds that into the cost of every round trip. On Hyperliquid, the explicit fee cost is zero. Some traders respond by overtrading because they do not feel the friction of commissions. This is a trap. The implicit cost of trading—the spread and slippage from moving the market with your order—still exists. A trader who enters and exits the same position frequently on Hyperliquid pays zero fees but can still lose money to spread and adverse price movement. Transparency and zero fees do not eliminate market economics; they make the remaining economics clearer.

Why institutional traders must rethink strategy on transparent order books

Institutional traders built many profitable strategies on centralized exchange market structures that Hyperliquid does not support. Strategies relying on dark pool order detection, predatory routing around liquidity, or advance knowledge of order flow patterns cannot be replicated on a transparent book. Market makers who profited from information asymmetry face a different competitive environment. This does not mean professional traders cannot profit on Hyperliquid; it means their edge must come from actual execution skill, market insight, and faster reaction times rather than from structural information advantages.

Some institutional traders are adapting by focusing on prediction and market-making across Hyperliquid and other transparent venues. If Ethereum perpetuals are trading at slightly different prices on Hyperliquid versus another DEX, and the gap is larger than the cost of moving capital and executing trades, that becomes a pure arbitrage opportunity visible to anyone watching both books. Sophisticated traders build infrastructure to spot these opportunities faster and execute the trades before they disappear. This is different from the dark pool game, but it rewards speed, capital efficiency, and technical sophistication in the same way.

Another institutional strategy shift involves taking advantage of the zero-fee structure to engage in tighter market-making. On a centralized exchange, a market maker might post spreads of 2 basis points but charge themselves 1 basis point in fees, resulting in net revenue of 1 basis point per round trip. On Hyperliquid, they can post spreads of 1 basis point with zero fees and double their revenue per round trip if volume remains constant. This incentive drives competition and tighter spreads across the board. The traders who benefit most are those willing to use the transparent, low-cost infrastructure to their advantage rather than trying to recreate dark pool dynamics that never existed on-chain.

Market structure evolution and the future of retail access

The longer-term significance of Hyperliquid’s transparent order book is structural. As more trading volume migrates to fully on-chain venues, the advantages of centralized dark pools erode. Market makers and traders have less reason to fragment their liquidity across multiple platforms if one platform offers zero fees, transparent execution, and regulatory clarity. This does not mean centralized exchanges disappear; it means they must compete on different terms. Some will transition to offering onboarding fiat services and simplified custody rather than proprietary trading advantages. Others may attempt to remain opaque, but they will face competition from venues that offer the opposite.

For retail traders, the practical effect is a reduction in structural disadvantage. The information asymmetry that institutional traders and market makers exploited for decades was profitable precisely because retail traders could not see order flow, could not verify execution, and could not compare prices across dark pools. On a transparent book, a retail trader with basic market sense and reasonable execution discipline can avoid the worst outcomes. They cannot beat professional traders consistently, but they can stop being harvested by structural opacity.

The remaining edge belongs to traders who understand market structure and leverage it. This might mean timing orders to coincide with known liquidity events, using limit orders strategically instead of market orders, or building positions across time based on public order book patterns. The transparency advantage is not that anyone can suddenly profit; it is that profit and loss becomes a function of actual trading skill rather than information privilege that cannot be accessed. For traders moving from centralized exchanges to Hyperliquid, that shift alone justifies the adjustment period.

Frequently asked questions

What is a dark pool and why do retail traders lose money in them?

A dark pool is a private trading venue where orders are matched away from the public order book, typically on centralized exchanges. Retail traders do not know whether their orders are being filled in a dark pool or at a worse price than what was available on the lit book. Market makers with information about dark pool flow can adjust public quotes to profit before retail orders reach the visible order book. Hyperliquid eliminates dark pools entirely by making all orders visible on the transparent blockchain.

How does an on-chain order book prevent information asymmetry?

Every order posted to an on-chain order book is immediately visible to all participants. There is no privileged early access and no hidden matching engines. When a trade executes, it is recorded on the blockchain and can be verified by anyone. This means no participant has the advantage of seeing orders before others, and no venue operator can profit by routing orders to themselves or affiliated market makers without everyone seeing it happen.

Can retail traders actually make money on a transparent order book like Hyperliquid?

Yes, but profitability depends on skill rather than information privilege. The transparency eliminates one structural disadvantage retail traders face on centralized exchanges. Retail traders can still lose money through poor timing, overleveraging, or bad market predictions. However, they no longer lose money specifically because their broker hid better prices or routed their order to a dark pool. Success on a transparent book comes from understanding order book dynamics, using limit orders effectively, and managing position sizing—the same factors that separate profitable traders from unprofitable ones everywhere.

Hyperliquid’s Order Book Transparency vs. CEX Dark Pools: Why Real-Time Visibility Changes Trading Strategy

A retail trader places a market order for 10 Bitcoin perpetuals on a centralized exchange. The order is instantly filled, but at a price that moved 15 basis points against them between the moment they clicked submit and execution. They do not know whether that slippage came from market movement, their broker’s routing decision, or a dark pool matching engine designed to extract value from retail flow. On Hyperliquid, the same order would execute against a fully visible on-chain order book where every bid, ask, and pending order is observable in real time by every participant. The execution price is not a surprise; it is a transparent outcome of supply and demand that can be verified before and after settlement.

That structural difference creates a material advantage for traders willing to understand it. Centralized exchanges have long relied on information opacity to manage order flow and optimize routing in their own interests. Their dark pools, internal matching engines, and opaque pricing create a zone where institutional traders with market-making arrangements and technology investments can extract consistent value from retail participants who cannot see what is actually happening underneath the trading interface. Hyperliquid’s hyperliquid-dex.com eliminates that asymmetry by making the order book itself a public resource. Every trader sees the same quotes, the same depth, and the same execution prices. The consequence is not free money. It is a level where skill, speed, and strategy matter more than information privilege.

How dark pools create invisible information asymmetry

A dark pool is a private trading venue operated by a centralized exchange or independent broker where orders are matched away from the public order book. On most major exchanges, a significant percentage of order flow—sometimes 30 to 50 percent—never touches the lit book. A retail trader entering a market order on Binance or Coinbase has no visibility into what portion of their order is being filled in a dark pool, at what price, or whether their flow is being sent to a market maker that benefits from seeing the order first.

The economic logic is straightforward. An exchange or broker operator has a financial incentive to internalize order flow because it creates a spread between what they pay the seller and charge the buyer. If they can match retail buy orders against retail sell orders without posting to a public book, they pocket the difference. If retail flow is imbalanced—more buyers than sellers, for example—they can route that flow to affiliated market makers who will fill it at a price slightly worse than the lit book but better than the retail trader might get elsewhere. The retail trader feels they got filled quickly and at a “reasonable” price. They do not see the alternative execution that was possible or the venue where their order actually settled.

This structure also creates a hidden information advantage. When a market maker on an exchange sees that large buy orders are coming into dark pools, they can adjust their public quotes upward before those buyers reach the lit book. By the time a retail trader’s limit order reaches the public order book, the price has already moved. The trader was outrun by an information signal they could not access. Institutional traders with co-location rights, direct exchange connections, and relationships with market makers benefit from seeing order flow patterns that retail participants cannot. The fee structure reinforces this: some exchanges charge less for high-volume traders or market makers and more for retail, directly subsidizing the information advantage.

Why fully transparent on-chain order books change the execution calculus

An on-chain order book operates on a completely different principle. Every order—bid, ask, cancellation, partial fill—is recorded on the blockchain in a transaction that every node validates and stores. There is no dark pool, no internal matching engine, and no hidden flow. When a trader places a limit order on Hyperliquid, that order becomes visible to all other participants immediately. They can see the exact price, the quantity, and the time it entered the book. When their own market order executes, they can see which orders it filled against and verify the prices on the blockchain itself.

This eliminates the information asymmetry in two ways. First, no participant has privileged early sight of orders. Everyone watching the blockchain sees orders at the same time. A market maker cannot route retail flow to themselves; their quotes are submitted to the same book as everyone else. Second, execution cannot be hidden. The transaction that fills an order is immutable and publicly queryable. A trader can verify the exact price they received and confirm that no better price was available at that moment on the book. There is no “best execution” argument because execution was transparent and deterministic.

The mechanics of this transparency also create behavioral effects. Because every limit order is visible, competitors can see what prices are defended and what gaps exist. This tends to reduce the spreads that market makers can maintain without being filled immediately. Because orders cannot be hidden until the moment of execution, traders cannot use dark pools to mask large positions. A trader building a large position must either move the market with visible orders or split their intentions across time. These are not slight improvements; they are fundamental structural differences that alter the risk-reward of various trading strategies.

Comparing liquidity depth: transparency versus convenience

The question many traders ask is whether a fully transparent, decentralized perpetual exchange can offer the same liquidity depth and spread quality as a centralized platform with years of market-maker relationships and order flow concentration. This is where CEX performance and DEX transparency must be evaluated together rather than treated as mutually exclusive. Hyperliquid has attracted significant liquidity because its transparent order book and zero trading fees eliminate the economic incentive for market makers to fragment their capital across multiple venues. If a market maker can operate on a fully transparent book with no fees and no custodial risk, they can afford to provide deeper quotes than they would on a platform where they compete against dark pools and information asymmetries.

The execution speed on Hyperliquid is designed to match or exceed CEX performance. The platform processes orders with sub-millisecond latency and settles them on-chain without requiring withdrawal or deposit delays between trades. A trader moving from a centralized exchange may initially feel that tighter spreads and faster execution are not guaranteed. However, the structure creates incentives for the opposite. A market maker on a transparent book serves the public at whatever spread they choose; if that spread is too wide, someone else will post a tighter quote. The competitive pressure is immediate and verifiable. On a centralized exchange, a market maker can widen spreads based on internalized order flow patterns that no one else can see.

The practical difference becomes visible during volatility. On a centralized exchange, spreads widen when volume surges because market makers reduce their size and the exchange’s dark pool matching engine can no longer fully hide large orders. On Hyperliquid, spreads can widen, but the widening happens at a single, transparent price level visible to all participants. No trader is surprised by a fill that disappeared into an opaque matching engine. The same market-making physics apply, but the information is distributed equally.

How retail traders can exploit on-chain visibility for execution advantage

The simplest advantage of transparent order book trading is order placement strategy. A retail trader can see exactly where liquidity sits and where gaps exist. If a perpetual contract for Ethereum is trading with $500,000 in bids at $2,350 and $400,000 in asks at $2,351, that trader knows exactly what they are bidding into or offering against. On a centralized exchange, the trader sees the public book but not the dark pool flow that might execute their order at a worse price. On Hyperliquid, what they see is what they get.

This visibility advantage compounds for limit orders. A trader can post a limit order to buy Bitcoin perps at a specific price and know that if their order is filled, it filled against orders actually posted to the visible book. They do not need to worry that their order was filled against a dark pool fill that would not have been available if the venue had been transparent. They also can observe when their orders are filled and by how much, allowing them to refine their pricing strategy in real time. If an order does not fill for several seconds, they can examine the order book and understand why.

For swing traders and position builders, on-chain visibility reveals something critical about order flow patterns. A trader watching the Hyperliquid order book for Bitcoin perpetuals can see when large orders are being accumulated by other participants. If bid-side depth suddenly increases, it suggests either new buyers entering or long positions being accumulated. If that same depth disappears quickly, it suggests positions being liquidated or closed. These are pure signals of market behavior that are valuable for directional decisions. On a centralized exchange, some of that signal is hidden in dark pools or is captured privately by the exchange’s own market makers.

Advanced traders can also use the transparent order book to execute large positions with minimal slippage. Instead of entering a market order that moves the price against them, they can observe the standing liquidity and decide whether to pick off small orders across multiple price levels or split their order across time. The blockchain records every trade, so a sophisticated trader can analyze historical patterns and optimize execution timing. This kind of analysis is available on centralized exchanges too, but on Hyperliquid it is based on transparent ground truth rather than whatever order flow the exchange chose to disclose.

The behavioral shift required to adapt from CEX to decentralized perpetual exchanges

A trader switching from a centralized exchange to a fully transparent decentralized perpetual exchange must adjust several habits. The first adjustment is accepting that the order book is the market, not a representation of it. On a centralized exchange, a trader mentally maps the visible book to some larger true market that includes dark pools. On Hyperliquid, the visible book is the complete market for that instrument. This is simpler in principle but requires a mindset shift. The trader must stop wondering if a better price exists elsewhere and start understanding that if it did, it would be on the same book.

The second adjustment is becoming comfortable with your own order visibility. Because limits orders are posted publicly, other traders can see your intentions. This sounds disadvantageous, but it reverses an asymmetry that favors market makers on centralized exchanges. On a CEX, market makers see your order and can adjust their quotes before you fill. On Hyperliquid, if a market maker moves quotes after you post a limit order, they are moving the market publicly, and you can respond. The psychology shifts from “my order is hidden until I hit execute” to “my order is part of the market.” Experienced limit-order traders often find this less stressful once they adjust because the market is not secretly moving against them.

The third adjustment is treating zero fees differently. On a centralized exchange, a trader paying 0.05 percent in commissions adds that into the cost of every round trip. On Hyperliquid, the explicit fee cost is zero. Some traders respond by overtrading because they do not feel the friction of commissions. This is a trap. The implicit cost of trading—the spread and slippage from moving the market with your order—still exists. A trader who enters and exits the same position frequently on Hyperliquid pays zero fees but can still lose money to spread and adverse price movement. Transparency and zero fees do not eliminate market economics; they make the remaining economics clearer.

Why institutional traders must rethink strategy on transparent order books

Institutional traders built many profitable strategies on centralized exchange market structures that Hyperliquid does not support. Strategies relying on dark pool order detection, predatory routing around liquidity, or advance knowledge of order flow patterns cannot be replicated on a transparent book. Market makers who profited from information asymmetry face a different competitive environment. This does not mean professional traders cannot profit on Hyperliquid; it means their edge must come from actual execution skill, market insight, and faster reaction times rather than from structural information advantages.

Some institutional traders are adapting by focusing on prediction and market-making across Hyperliquid and other transparent venues. If Ethereum perpetuals are trading at slightly different prices on Hyperliquid versus another DEX, and the gap is larger than the cost of moving capital and executing trades, that becomes a pure arbitrage opportunity visible to anyone watching both books. Sophisticated traders build infrastructure to spot these opportunities faster and execute the trades before they disappear. This is different from the dark pool game, but it rewards speed, capital efficiency, and technical sophistication in the same way.

Another institutional strategy shift involves taking advantage of the zero-fee structure to engage in tighter market-making. On a centralized exchange, a market maker might post spreads of 2 basis points but charge themselves 1 basis point in fees, resulting in net revenue of 1 basis point per round trip. On Hyperliquid, they can post spreads of 1 basis point with zero fees and double their revenue per round trip if volume remains constant. This incentive drives competition and tighter spreads across the board. The traders who benefit most are those willing to use the transparent, low-cost infrastructure to their advantage rather than trying to recreate dark pool dynamics that never existed on-chain.

Market structure evolution and the future of retail access

The longer-term significance of Hyperliquid’s transparent order book is structural. As more trading volume migrates to fully on-chain venues, the advantages of centralized dark pools erode. Market makers and traders have less reason to fragment their liquidity across multiple platforms if one platform offers zero fees, transparent execution, and regulatory clarity. This does not mean centralized exchanges disappear; it means they must compete on different terms. Some will transition to offering onboarding fiat services and simplified custody rather than proprietary trading advantages. Others may attempt to remain opaque, but they will face competition from venues that offer the opposite.

For retail traders, the practical effect is a reduction in structural disadvantage. The information asymmetry that institutional traders and market makers exploited for decades was profitable precisely because retail traders could not see order flow, could not verify execution, and could not compare prices across dark pools. On a transparent book, a retail trader with basic market sense and reasonable execution discipline can avoid the worst outcomes. They cannot beat professional traders consistently, but they can stop being harvested by structural opacity.

The remaining edge belongs to traders who understand market structure and leverage it. This might mean timing orders to coincide with known liquidity events, using limit orders strategically instead of market orders, or building positions across time based on public order book patterns. The transparency advantage is not that anyone can suddenly profit; it is that profit and loss becomes a function of actual trading skill rather than information privilege that cannot be accessed. For traders moving from centralized exchanges to Hyperliquid, that shift alone justifies the adjustment period.

Frequently asked questions

What is a dark pool and why do retail traders lose money in them?

A dark pool is a private trading venue where orders are matched away from the public order book, typically on centralized exchanges. Retail traders do not know whether their orders are being filled in a dark pool or at a worse price than what was available on the lit book. Market makers with information about dark pool flow can adjust public quotes to profit before retail orders reach the visible order book. Hyperliquid eliminates dark pools entirely by making all orders visible on the transparent blockchain.

How does an on-chain order book prevent information asymmetry?

Every order posted to an on-chain order book is immediately visible to all participants. There is no privileged early access and no hidden matching engines. When a trade executes, it is recorded on the blockchain and can be verified by anyone. This means no participant has the advantage of seeing orders before others, and no venue operator can profit by routing orders to themselves or affiliated market makers without everyone seeing it happen.

Can retail traders actually make money on a transparent order book like Hyperliquid?

Yes, but profitability depends on skill rather than information privilege. The transparency eliminates one structural disadvantage retail traders face on centralized exchanges. Retail traders can still lose money through poor timing, overleveraging, or bad market predictions. However, they no longer lose money specifically because their broker hid better prices or routed their order to a dark pool. Success on a transparent book comes from understanding order book dynamics, using limit orders effectively, and managing position sizing—the same factors that separate profitable traders from unprofitable ones everywhere.

Hyperliquid’s Order Book Transparency vs. CEX Dark Pools: Why Real-Time Visibility Changes Trading Strategy

A retail trader places a market order for 10 Bitcoin perpetuals on a centralized exchange. The order is instantly filled, but at a price that moved 15 basis points against them between the moment they clicked submit and execution. They do not know whether that slippage came from market movement, their broker’s routing decision, or a dark pool matching engine designed to extract value from retail flow. On Hyperliquid, the same order would execute against a fully visible on-chain order book where every bid, ask, and pending order is observable in real time by every participant. The execution price is not a surprise; it is a transparent outcome of supply and demand that can be verified before and after settlement.

That structural difference creates a material advantage for traders willing to understand it. Centralized exchanges have long relied on information opacity to manage order flow and optimize routing in their own interests. Their dark pools, internal matching engines, and opaque pricing create a zone where institutional traders with market-making arrangements and technology investments can extract consistent value from retail participants who cannot see what is actually happening underneath the trading interface. Hyperliquid’s hyperliquid-dex.com eliminates that asymmetry by making the order book itself a public resource. Every trader sees the same quotes, the same depth, and the same execution prices. The consequence is not free money. It is a level where skill, speed, and strategy matter more than information privilege.

How dark pools create invisible information asymmetry

A dark pool is a private trading venue operated by a centralized exchange or independent broker where orders are matched away from the public order book. On most major exchanges, a significant percentage of order flow—sometimes 30 to 50 percent—never touches the lit book. A retail trader entering a market order on Binance or Coinbase has no visibility into what portion of their order is being filled in a dark pool, at what price, or whether their flow is being sent to a market maker that benefits from seeing the order first.

The economic logic is straightforward. An exchange or broker operator has a financial incentive to internalize order flow because it creates a spread between what they pay the seller and charge the buyer. If they can match retail buy orders against retail sell orders without posting to a public book, they pocket the difference. If retail flow is imbalanced—more buyers than sellers, for example—they can route that flow to affiliated market makers who will fill it at a price slightly worse than the lit book but better than the retail trader might get elsewhere. The retail trader feels they got filled quickly and at a “reasonable” price. They do not see the alternative execution that was possible or the venue where their order actually settled.

This structure also creates a hidden information advantage. When a market maker on an exchange sees that large buy orders are coming into dark pools, they can adjust their public quotes upward before those buyers reach the lit book. By the time a retail trader’s limit order reaches the public order book, the price has already moved. The trader was outrun by an information signal they could not access. Institutional traders with co-location rights, direct exchange connections, and relationships with market makers benefit from seeing order flow patterns that retail participants cannot. The fee structure reinforces this: some exchanges charge less for high-volume traders or market makers and more for retail, directly subsidizing the information advantage.

Why fully transparent on-chain order books change the execution calculus

An on-chain order book operates on a completely different principle. Every order—bid, ask, cancellation, partial fill—is recorded on the blockchain in a transaction that every node validates and stores. There is no dark pool, no internal matching engine, and no hidden flow. When a trader places a limit order on Hyperliquid, that order becomes visible to all other participants immediately. They can see the exact price, the quantity, and the time it entered the book. When their own market order executes, they can see which orders it filled against and verify the prices on the blockchain itself.

This eliminates the information asymmetry in two ways. First, no participant has privileged early sight of orders. Everyone watching the blockchain sees orders at the same time. A market maker cannot route retail flow to themselves; their quotes are submitted to the same book as everyone else. Second, execution cannot be hidden. The transaction that fills an order is immutable and publicly queryable. A trader can verify the exact price they received and confirm that no better price was available at that moment on the book. There is no “best execution” argument because execution was transparent and deterministic.

The mechanics of this transparency also create behavioral effects. Because every limit order is visible, competitors can see what prices are defended and what gaps exist. This tends to reduce the spreads that market makers can maintain without being filled immediately. Because orders cannot be hidden until the moment of execution, traders cannot use dark pools to mask large positions. A trader building a large position must either move the market with visible orders or split their intentions across time. These are not slight improvements; they are fundamental structural differences that alter the risk-reward of various trading strategies.

Comparing liquidity depth: transparency versus convenience

The question many traders ask is whether a fully transparent, decentralized perpetual exchange can offer the same liquidity depth and spread quality as a centralized platform with years of market-maker relationships and order flow concentration. This is where CEX performance and DEX transparency must be evaluated together rather than treated as mutually exclusive. Hyperliquid has attracted significant liquidity because its transparent order book and zero trading fees eliminate the economic incentive for market makers to fragment their capital across multiple venues. If a market maker can operate on a fully transparent book with no fees and no custodial risk, they can afford to provide deeper quotes than they would on a platform where they compete against dark pools and information asymmetries.

The execution speed on Hyperliquid is designed to match or exceed CEX performance. The platform processes orders with sub-millisecond latency and settles them on-chain without requiring withdrawal or deposit delays between trades. A trader moving from a centralized exchange may initially feel that tighter spreads and faster execution are not guaranteed. However, the structure creates incentives for the opposite. A market maker on a transparent book serves the public at whatever spread they choose; if that spread is too wide, someone else will post a tighter quote. The competitive pressure is immediate and verifiable. On a centralized exchange, a market maker can widen spreads based on internalized order flow patterns that no one else can see.

The practical difference becomes visible during volatility. On a centralized exchange, spreads widen when volume surges because market makers reduce their size and the exchange’s dark pool matching engine can no longer fully hide large orders. On Hyperliquid, spreads can widen, but the widening happens at a single, transparent price level visible to all participants. No trader is surprised by a fill that disappeared into an opaque matching engine. The same market-making physics apply, but the information is distributed equally.

How retail traders can exploit on-chain visibility for execution advantage

The simplest advantage of transparent order book trading is order placement strategy. A retail trader can see exactly where liquidity sits and where gaps exist. If a perpetual contract for Ethereum is trading with $500,000 in bids at $2,350 and $400,000 in asks at $2,351, that trader knows exactly what they are bidding into or offering against. On a centralized exchange, the trader sees the public book but not the dark pool flow that might execute their order at a worse price. On Hyperliquid, what they see is what they get.

This visibility advantage compounds for limit orders. A trader can post a limit order to buy Bitcoin perps at a specific price and know that if their order is filled, it filled against orders actually posted to the visible book. They do not need to worry that their order was filled against a dark pool fill that would not have been available if the venue had been transparent. They also can observe when their orders are filled and by how much, allowing them to refine their pricing strategy in real time. If an order does not fill for several seconds, they can examine the order book and understand why.

For swing traders and position builders, on-chain visibility reveals something critical about order flow patterns. A trader watching the Hyperliquid order book for Bitcoin perpetuals can see when large orders are being accumulated by other participants. If bid-side depth suddenly increases, it suggests either new buyers entering or long positions being accumulated. If that same depth disappears quickly, it suggests positions being liquidated or closed. These are pure signals of market behavior that are valuable for directional decisions. On a centralized exchange, some of that signal is hidden in dark pools or is captured privately by the exchange’s own market makers.

Advanced traders can also use the transparent order book to execute large positions with minimal slippage. Instead of entering a market order that moves the price against them, they can observe the standing liquidity and decide whether to pick off small orders across multiple price levels or split their order across time. The blockchain records every trade, so a sophisticated trader can analyze historical patterns and optimize execution timing. This kind of analysis is available on centralized exchanges too, but on Hyperliquid it is based on transparent ground truth rather than whatever order flow the exchange chose to disclose.

The behavioral shift required to adapt from CEX to decentralized perpetual exchanges

A trader switching from a centralized exchange to a fully transparent decentralized perpetual exchange must adjust several habits. The first adjustment is accepting that the order book is the market, not a representation of it. On a centralized exchange, a trader mentally maps the visible book to some larger true market that includes dark pools. On Hyperliquid, the visible book is the complete market for that instrument. This is simpler in principle but requires a mindset shift. The trader must stop wondering if a better price exists elsewhere and start understanding that if it did, it would be on the same book.

The second adjustment is becoming comfortable with your own order visibility. Because limits orders are posted publicly, other traders can see your intentions. This sounds disadvantageous, but it reverses an asymmetry that favors market makers on centralized exchanges. On a CEX, market makers see your order and can adjust their quotes before you fill. On Hyperliquid, if a market maker moves quotes after you post a limit order, they are moving the market publicly, and you can respond. The psychology shifts from “my order is hidden until I hit execute” to “my order is part of the market.” Experienced limit-order traders often find this less stressful once they adjust because the market is not secretly moving against them.

The third adjustment is treating zero fees differently. On a centralized exchange, a trader paying 0.05 percent in commissions adds that into the cost of every round trip. On Hyperliquid, the explicit fee cost is zero. Some traders respond by overtrading because they do not feel the friction of commissions. This is a trap. The implicit cost of trading—the spread and slippage from moving the market with your order—still exists. A trader who enters and exits the same position frequently on Hyperliquid pays zero fees but can still lose money to spread and adverse price movement. Transparency and zero fees do not eliminate market economics; they make the remaining economics clearer.

Why institutional traders must rethink strategy on transparent order books

Institutional traders built many profitable strategies on centralized exchange market structures that Hyperliquid does not support. Strategies relying on dark pool order detection, predatory routing around liquidity, or advance knowledge of order flow patterns cannot be replicated on a transparent book. Market makers who profited from information asymmetry face a different competitive environment. This does not mean professional traders cannot profit on Hyperliquid; it means their edge must come from actual execution skill, market insight, and faster reaction times rather than from structural information advantages.

Some institutional traders are adapting by focusing on prediction and market-making across Hyperliquid and other transparent venues. If Ethereum perpetuals are trading at slightly different prices on Hyperliquid versus another DEX, and the gap is larger than the cost of moving capital and executing trades, that becomes a pure arbitrage opportunity visible to anyone watching both books. Sophisticated traders build infrastructure to spot these opportunities faster and execute the trades before they disappear. This is different from the dark pool game, but it rewards speed, capital efficiency, and technical sophistication in the same way.

Another institutional strategy shift involves taking advantage of the zero-fee structure to engage in tighter market-making. On a centralized exchange, a market maker might post spreads of 2 basis points but charge themselves 1 basis point in fees, resulting in net revenue of 1 basis point per round trip. On Hyperliquid, they can post spreads of 1 basis point with zero fees and double their revenue per round trip if volume remains constant. This incentive drives competition and tighter spreads across the board. The traders who benefit most are those willing to use the transparent, low-cost infrastructure to their advantage rather than trying to recreate dark pool dynamics that never existed on-chain.

Market structure evolution and the future of retail access

The longer-term significance of Hyperliquid’s transparent order book is structural. As more trading volume migrates to fully on-chain venues, the advantages of centralized dark pools erode. Market makers and traders have less reason to fragment their liquidity across multiple platforms if one platform offers zero fees, transparent execution, and regulatory clarity. This does not mean centralized exchanges disappear; it means they must compete on different terms. Some will transition to offering onboarding fiat services and simplified custody rather than proprietary trading advantages. Others may attempt to remain opaque, but they will face competition from venues that offer the opposite.

For retail traders, the practical effect is a reduction in structural disadvantage. The information asymmetry that institutional traders and market makers exploited for decades was profitable precisely because retail traders could not see order flow, could not verify execution, and could not compare prices across dark pools. On a transparent book, a retail trader with basic market sense and reasonable execution discipline can avoid the worst outcomes. They cannot beat professional traders consistently, but they can stop being harvested by structural opacity.

The remaining edge belongs to traders who understand market structure and leverage it. This might mean timing orders to coincide with known liquidity events, using limit orders strategically instead of market orders, or building positions across time based on public order book patterns. The transparency advantage is not that anyone can suddenly profit; it is that profit and loss becomes a function of actual trading skill rather than information privilege that cannot be accessed. For traders moving from centralized exchanges to Hyperliquid, that shift alone justifies the adjustment period.

Frequently asked questions

What is a dark pool and why do retail traders lose money in them?

A dark pool is a private trading venue where orders are matched away from the public order book, typically on centralized exchanges. Retail traders do not know whether their orders are being filled in a dark pool or at a worse price than what was available on the lit book. Market makers with information about dark pool flow can adjust public quotes to profit before retail orders reach the visible order book. Hyperliquid eliminates dark pools entirely by making all orders visible on the transparent blockchain.

How does an on-chain order book prevent information asymmetry?

Every order posted to an on-chain order book is immediately visible to all participants. There is no privileged early access and no hidden matching engines. When a trade executes, it is recorded on the blockchain and can be verified by anyone. This means no participant has the advantage of seeing orders before others, and no venue operator can profit by routing orders to themselves or affiliated market makers without everyone seeing it happen.

Can retail traders actually make money on a transparent order book like Hyperliquid?

Yes, but profitability depends on skill rather than information privilege. The transparency eliminates one structural disadvantage retail traders face on centralized exchanges. Retail traders can still lose money through poor timing, overleveraging, or bad market predictions. However, they no longer lose money specifically because their broker hid better prices or routed their order to a dark pool. Success on a transparent book comes from understanding order book dynamics, using limit orders effectively, and managing position sizing—the same factors that separate profitable traders from unprofitable ones everywhere.