Die Welt des Online-Glücksspiels bietet unzählige Möglichkeiten für Spieler, aber was unterscheidet die besten Plattformen von den durchschnittlichen? Die Antwort liegt oft in den exklusiven Angeboten für treue Kunden. VIP-Programme und Treuepunkte sind zentral für die migliori siti scommesse, die langfristige Kundenbeziehungen pflegen. Diese Belohnungssysteme können den Unterschied zwischen einem einfachen Spielerlebnis und einem herausragenden Gaming-Erlebnis ausmachen. Spieler, die ihre Favoriten unter den siti scommesse auswählen, sollten genau prüfen, welche Vorteile sie als treue Kunden erwarten können. Wer nach einer Plattform sucht, die seine Treue honoriert, sollte sich über die Kriterien für die besten bookmaker online informieren. Ein guter jack-casino-bet.net zeichnet sich durch transparente und lukrative Treueprogramme aus.
VIP-Programme im Online-Glücksspiel
VIP-Programme sind ein wesentlicher Bestandteil vieler siti scommesse online, die Wert auf langfristige Kundenbindung legen. Diese Programme sind speziell für Spieler konzipiert, die regelmäßig auf der Plattform aktiv sind und höhere Einsätze tätigen. Die Vorteile reichen von schnelleren Auszahlungen über persönliche Account-Manager bis hin zu exklusiven Bonusangeboten, die nicht für alle Spieler verfügbar sind. Die besten siti di scommesse sportive heben sich oft durch ihre durchdachten VIP-Stufen ab, die Spieler motivieren, ihre Aktivitäten zu steigern.
Was sind VIP-Programme?
VIP-Programme sind Treuebelohnungssysteme, die von Online-Casinos und Buchmachern angeboten werden, um ihre wertvollsten Kunden zu würdigen. Spieler können verschiedene Stufen erreichen, je nachdem, wie viel sie spielen und wie aktiv sie sind. Jede Stufe bringt zusätzliche Privilegien mit sich, von verbesserten Boni bis hin zu Einladungen zu exklusiven Events. Details zu Bonusbedingungen und Spielauswahl gibt es direkt bei Jack Bonus ohne Einzahlung. Die migliori siti scommesse verstehen, dass ihre VIP-Spieler nicht nur hohe Einsätze tätigen, sondern auch als Botschafter für die Plattform wirken.
Vorteile für VIP-Spieler
Als VIP-Spieler genießen Sie zahlreiche Vorteile, die über das normale Spielerlebnis hinausgehen. Dazu gehören höhere Bonusangebote, persönliche Support-Mitarbeiter, schnellere Auszahlungen und manchmal sogar Geschenke oder Reisen. Die besten siti scommesse bonus locken neue Kunden mit großzügigen Willkommensangeboten, aber es sind die Treueprogramme, die langfristige Kunden binden. Wer regelmäßig auf den bookmaker online Plattformen spielt, sollte sich unbedingt über die VIP-Vorteile informieren, die ihm zustehen könnten.
Treuepunkte: Wie funktionieren sie?
Treuepunkte sind ein weiteres Belohnungssystem, das in vielen siti scommesse online zu finden ist. Im Gegensatz zu VIP-Programmen, die oft auf Einladung basieren, können fast alle Spieler Treuepunkte sammeln. Jede Wette oder jeder Casino-Einsatz bringt Punkte ein, die später gegen Boni, Freispiele oder andere Belohnungen eingetauscht werden können. Dieses System motiviert Spieler, weiterhin auf der Plattforme aktiv zu bleiben, da sie direkt von ihrer Treue profitieren.
Das Sammeln von Treuepunkten
Das Sammeln von Treuepunkten ist einfach: Für jeden Einsatz erhalten Sie eine bestimmte Anzahl an Punkten. Die genaue Formel variiert zwischen den verschiedenen siti di scommesse sportive, aber im Allgemeinen gilt: Je höher Ihr Einsatz, desto mehr Punkte sammeln Sie. Manche Plattformen bieten auch doppelte Punkte für bestimmte Spiele oder Events an. Die migliori siti scommesse machen es ihren Spielern leicht, ihren Punktestand zu verfolgen und die verfügbaren Belohnungen einzusehen.
Einlösen von Treuepunkten
Sobald Sie genügend Treuepunkte gesammelt haben, können Sie diese gegen verschiedene Belohnungen eintauschen. Beliebte Optionen include Bonusguthaben, Freispiele für Slots, Cashback-Angebote oder sogar Einladungen zu exklusiven Events. Die besten siti scommesse bonus bieten ihren Spielern flexible Möglichkeiten, ihre Punkte einzulösen, sodass jeder nach seinen Vorlieben profitieren kann. Ein bookmaker online, der Treuepunkte fair und transparent verwaltet, schafft Vertrauen und langfristige Zufriedenheit bei seinen Spielern.
Vergleich von Treueprogrammen
Nicht alle Treueprogramme sind gleich geschaffen. Die Qualität variiert erheblich zwischen den verschiedenen siti scommesse online. Während einige Anbieter nur minimale Belohnungen bieten, überzeugen andere mit durchdachten Systemen, die wirklich lohnenswert sind. Ein Vergleich der verschiedenen Programme kann Spielern helfen, die Plattform zu finden, die am besten zu ihren Spielgewohnheiten und -präferenzen passt.
| Plattform |
VIP-Stufen |
Treuepunkte-System |
Exklusive Vorteile |
| Plattform A |
5 Stufen |
1 Punkt pro 5 € Einsatz |
Persönlicher Account Manager |
| Plattform B |
3 Stufen |
1 Punkt pro 10 € Einsatz |
Schnellere Auszahlungen |
| Plattform C |
4 Stufen |
1 Punkt pro 7 € Einsatz |
Exklusive Boni und Geschenke |
| Plattform D |
6 Stufen |
1 Punkt pro 4 € Einsatz |
Einladungen zu Events |
| Plattform E |
2 Stufen |
1 Punkt pro 8 € Einsatz |
Cashback Angebote |
Wie man das Beste aus Treueprogrammen herausholt
Um das Maximum aus den Treueprogrammen der siti scommesse online herauszuholen, ist es wichtig, die Regeln und Bedingungen genau zu verstehen. Informieren Sie sich über die Umsatzanforderungen für Boni und die Gültigkeitsdauer der gesammelten Punkte. Die migliori siti scommesse bieten transparente Bedingungen, die es Ihnen erleichtern, die Vorteile voll auszuschöpfen. Planen Sie Ihr Spielbudget strategisch, um gleichzeitig unterhaltsam zu spielen und Treuepunkte zu maximieren.
Strategisches Spielen
Eine strategische Herangehensweise an Ihr Spiel kann Ihnen helfen, mehr Treuepunkte zu sammeln. Planen Sie, welche Spiele oder Sportwetten Ihnen am meisten Punkte pro Einsatz bringen und konzentrieren Sie sich darauf. Die siti di scommesse sportive bieten oft höhere Punktequoten für bestimmte Sportarten oder Ereignisse. Informieren Sie sich über aktuelle Promotionen, bei denen Sie zusätzliche Punkte oder doppelte Punkte erhalten können, um Ihre Belohnungen zu maximieren.
Den Überblick behalten
Behalten Sie stets den Überblick über Ihre gesammelten Punkte und die verfügbaren Belohnungen. Die besten siti scommesse bonus bieten einen übersichtlichen Dashboard-Bereich, in dem Sie Ihren Punktestand einsehen und Belohnungen einlösen können. Überprüfen Sie regelmäßig, welche Vorteile für Sie als treuer Spieler verfügbar sind, und stellen Sie sicher, dass Sie keine wertvollen Boni verpassen. Ein gut organisiertes Treueprogramm kann Ihr Spielerlebnis erheblich verbessern und zusätzliche Unterhaltungswerte bieten.
Häufige Fragen
Sind VIP-Programme nur für High Roller?
Nein, viele siti scommesse online bieten verschiedene VIP-Stufen für unterschiedliche Spielerniveaus. Selbst mit moderaten Einsätzen können Sie bestimmte Vorteile erreichen, je nachdem, wie aktiv Sie spielen.
Kann ich meine Treuepunkte in Echtgeld umwandeln?
Die meisten bookmaker online erlauben den Umtausch von Treuepunkten gegen Bonusguthaben oder Freispiele. Ein direkter Umtausch in Echtgeld ist weniger üblich, aber einige Anbieter bieten diese Möglichkeit.
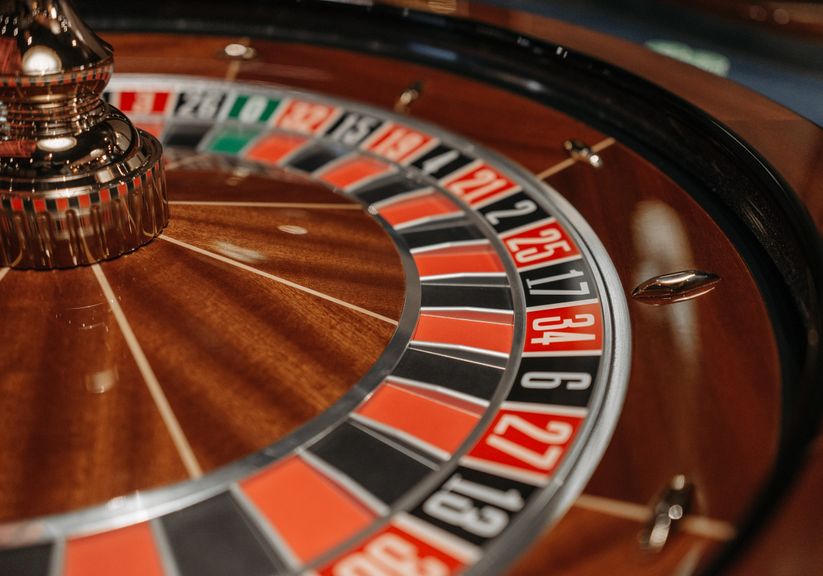
When the Easter calendar rolls around, casino floors and online lobbies alike see a noticeable surge in roulette traffic. The bright holiday atmosphere, combined with limited‑time promotions, creates a perfect storm of excitement that can tempt even the most disciplined player to chase the next spin. Yet the very factors that make the season alluring—extra bonuses, themed tournaments, and a festive mood—also raise the stakes of careless wagering.
Responsible play is the foundation of any lasting roulette strategy. For practical guidance on safe gambling habits, readers can turn to resources such as online casino singapore, which offers clear advice on setting limits and recognizing problem‑play signals. By pairing that mindset with proven bankroll tactics, selective betting systems, and the clever use of loyalty programmes, players can transform Easter’s sparkle into a calculated edge rather than a gamble on impulse.
In the sections that follow we will break down practical bankroll management, examine roulette systems that respect the odds, and show how loyalty rewards can effectively lower the house edge. The goal is to equip you with a playbook that balances thrill and discipline, so every spin during the holiday season adds value to your overall casino experience.
Understanding Roulette’s Risk Profile
Roulette’s allure lies in its simple premise: a single ball decides win or loss, yet the mathematics behind each spin are anything but trivial. The European wheel, with a single zero, carries a house edge of 2.70 %, while the American version adds a double zero, pushing the edge to 5.26 %. This difference translates directly into variance; the American layout produces more frequent swings, demanding a larger bankroll to weather losing streaks.
Seasonal promotions—Easter match‑play credits, free‑bet tokens, or “no‑risk” spins—can temporarily improve expected value, but they also encourage larger bet sizes. When a bonus inflates the perceived bankroll, players often underestimate the underlying edge, leading to overexposure. Understanding how each wheel type interacts with these offers is essential: a 10 % bonus on a European table still leaves the 2.70 % edge intact, whereas the same bonus on an American wheel masks a higher variance that can erode gains faster.
By quantifying the edge and variance before placing a bet, you can adjust stake size to match the true risk. This disciplined approach prevents the common Easter‑season pitfall of “bonus‑driven” over‑betting, keeping your bankroll aligned with the statistical realities of the game.
Core Principles of Effective Bankroll Management
Effective bankroll management separates casual players from those who consistently profit over time. The first step is to distinguish a session bankroll—the amount you are willing to risk in a single sitting—from a lifetime bankroll, the total capital allocated for roulette across weeks or months. Treating these as separate entities prevents a single lucky or unlucky session from jeopardising long‑term play.
A widely adopted guideline is the 1‑2‑5 % rule. For any individual bet, risk no more than 1 % of your session bankroll on low‑variance bets (e.g., even‑money splits), 2 % on medium‑risk bets (dozens or columns), and up to 5 % on high‑variance single‑number wagers. Applying this rule to an Easter tournament with a €500 session bankroll means a maximum single‑number bet of €25, preserving enough capital to survive inevitable downswings.
Stop‑loss and win‑lock thresholds add another layer of protection. Decide in advance the loss limit that will trigger an immediate exit (e.g., 30 % of the session bankroll) and a profit target that will be locked in (e.g., 50 % gain). During festive promotions, these thresholds become especially valuable, as the excitement can blur judgment.
Bet‑Size Ladder Technique
- Start Small – Begin with a base bet equal to 1 % of the session bankroll.
- Win Increment – After each win, move up one rung (increase bet by 1 % of the bankroll).
- Loss Reset – After a loss, drop back to the base bet or the previous rung, never below the base.
- Cap the Ladder – Set a maximum rung at 5 % of the bankroll to avoid runaway exposure.
This ladder allows you to capitalize on winning streaks while automatically curbing losses, keeping the overall variance within the limits set by the 1‑2‑5 % rule.
Tracking Tools and Apps
- Casino‑Tracker – Real‑time profit/loss dashboards, customizable alerts for stop‑loss limits.
- BetBuddy – Mobile app that logs each spin, calculates variance, and suggests optimal bet sizes.
- Spreadsheet Templates – Simple Google Sheets with built‑in formulas for bankroll percentage tracking.
Using any of these tools ensures you stay aware of your exposure throughout an Easter‑themed marathon, reinforcing disciplined decision‑making.
Roulette Systems That Actually Respect the Odds
The roulette community is saturated with systems promising guaranteed wins. Classic approaches like Martingale (doubling after each loss) and Labouchère (cancellation sequence) often crumble under table limits and deep losing streaks, especially on the more volatile American wheel. Fibonacci, while less aggressive, still suffers from the same fundamental flaw: it assumes infinite bankroll and ignores the house edge.
Two methods stand out for aligning with risk‑management theory.
Reverse‑Martingale (Paroli) – Instead of chasing losses, you increase the stake after each win, resetting after a loss. This leverages hot streaks while limiting exposure during cold runs. For example, start with a €10 bet; after three consecutive wins, you’d be at €80, then revert to €10 on the next loss.
3‑Bet Flat Betting – Place three equal bets on complementary sections (e.g., red, black, and a column) each spin. The total stake remains constant, and the expected loss per spin equals the house edge multiplied by the total wager. Because the bet size never fluctuates, bankroll variance stays low, making it ideal for players who prefer steady, predictable sessions during holiday promotions.
Both systems respect the underlying odds, avoid runaway bet escalation, and integrate smoothly with the bankroll rules outlined earlier.
Integrating Loyalty Programs into Your Strategy
Most reputable online casinos reward consistent play with points, tier upgrades, and cashback—elements that can materially offset the roulette house edge. Points earned per €1 wager often translate into bonus credits, while higher tiers unlock faster withdrawal limits, exclusive promotions, and personalized match‑play offers.
When evaluating a loyalty scheme, consider three metrics:
- Point‑per‑Bet Ratio – How many points are awarded for each unit wagered on roulette?
- Comp‑Gift Frequency – Are there regular freebies (e.g., free spins on table‑game slots) that can be converted into cash value?
- Tier‑Based Cashback – Does the program return a percentage of net losses as bonus cash?
By converting these benefits into an “effective house edge reduction,” you can quantify the true advantage of loyalty status. For instance, a 10 % cashback on net losses reduces a 2.70 % European edge to roughly 2.43 % for a high‑tier player.
Case Study: Turning a Mid‑Tier Loyalty Status into a Seasonal Edge
Emma, a mid‑tier member at a leading Singapore‑focused casino, entered an Easter weekend with a €1,000 lifetime bankroll. Her tier granted 0.5 % cashback on roulette losses and a 1 : 1 point conversion rate.
- Day 1: €200 session, €15 loss → €7.50 cashback credited.
- Day 2: €250 session, €30 win → no cashback, but points accumulated for a €10 free‑bet voucher.
- Day 3: €300 session, €20 loss → €10 cashback.
Total net loss after three days: €25. After applying €17.50 cashback and €10 voucher (used on a low‑variance even‑money bet), Emma’s effective loss dropped to €-2.50, turning a modest losing streak into a break‑even outcome. The loyalty programme effectively shaved roughly 1.5 % off her overall edge for the weekend.
Seasonal Bonuses: Easter Eggs Worth Hunting
Easter promotions come in many flavors, each with its own value proposition. Common offers include:
| Bonus Type |
Typical Value |
Wagering Requirement |
Ideal Use |
| Match‑Play Roulette Credit |
100 % up to €200 |
20× bonus amount |
Boosts session bankroll without extra risk |
| Free Spins on Table‑Game Slots |
20 spins @ 0.10 € each |
30× spin value |
Converts to cash for later roulette play |
| Cashback on Net Losses |
10 % up to €50 |
None |
Directly reduces effective house edge |
When assessing a bonus, calculate the “real value” by dividing the bonus amount by its wagering multiplier. A €200 match‑play credit with a 20× requirement yields an effective value of €10 per €1 wagered, whereas a 30× requirement on free spins reduces the effective value to roughly €3.33 per €1.
Prioritize offers that require low or no wagering, especially if you plan to stick to low‑variance bets. Match‑play credits are particularly powerful for Easter tournaments, as they effectively double your bankroll for the duration of the promotion, allowing you to apply the 1‑2‑5 % rule on a larger base without increasing actual risk.
Psychological Traps During Holiday Play
The festive atmosphere can cloud judgment, leading to three common psychological pitfalls:
- Holiday Hype Effect – The excitement of themed events creates a sense of urgency, prompting impulsive, larger bets.
- Loss Chasing – After a streak of bad luck, players may increase stake size to “recover” quickly, violating bankroll limits.
- Reward Overvaluation – Bonus alerts trigger dopamine spikes, making players overestimate the value of the offer.
To stay disciplined, adopt these techniques:
- Pre‑Game Ritual – Write down your session bankroll, stop‑loss, and win‑lock limits before logging in.
- Timed Breaks – Set a timer for every 30 minutes of play; step away for five minutes to reset focus.
- Mindfulness Cues – Use a simple breathing exercise when you feel the urge to increase a bet beyond the 5 % cap.
By integrating these habits, you reduce the influence of holiday‑induced adrenaline and keep decisions rooted in data rather than emotion.
Crafting a Personalized Roulette Playbook
A playbook consolidates all the elements discussed into a single, actionable worksheet. Below is a template you can adapt for an Easter weekend:
| Item |
Value |
Notes |
| Session bankroll |
€300 |
Fixed for Saturday, €200 for Sunday |
| Base bet (1 % rule) |
€3 |
Applied to even‑money bets |
| Max bet (5 % rule) |
€15 |
For single‑number wagers |
| Stop‑loss limit |
30 % of bankroll |
€90 (Sat), €60 (Sun) |
| Win‑lock target |
50 % gain |
€450 (Sat), €300 (Sun) |
| Loyalty tier |
Mid‑tier (0.5 % cashback) |
Expect €5‑€10 cashback |
| Bonus to use |
€100 match‑play credit |
Apply on first session only |
During the session, record each spin’s outcome, update the bankroll column, and adjust the “Bet‑Size Ladder” accordingly. This structured approach ensures every decision is traceable and aligned with your risk parameters.
Monitoring Progress & Adjusting Strategies Post‑Easter
After the holiday rush, review the following metrics:
- Win/Loss Ratio – Compare total wins to total losses; a ratio above 1.0 indicates a profitable session.
- Loyalty Point Efficiency – Divide points earned by total wagered amount; higher efficiency suggests the loyalty programme is adding value.
- Bankroll Variance – Calculate the standard deviation of bet sizes; a lower variance signals adherence to the 1‑2‑5 % rule.
If the variance is higher than expected, consider tightening the Bet‑Size Ladder or lowering the max‑bet percentage. Should loyalty point efficiency fall short, explore alternative programmes or focus on games with better point‑per‑bet ratios, such as live dealer roulette where some operators award extra points for real‑time play.
Adjustments for the next seasonal cycle might include:
- Switching to a higher tier by consolidating play on a single platform.
- Negotiating personalized Easter bonuses with the casino’s VIP desk.
- Incorporating a new flat‑bet system if the previous one produced excessive volatility.
Continuous refinement transforms each festive period into a learning opportunity, gradually improving both profitability and enjoyment.
Conclusion
Balancing the thrill of Easter‑themed roulette with disciplined risk management creates a sustainable path to long‑term success. By understanding the game’s inherent edge, applying strict bankroll rules, selecting systems that respect odds, and leveraging loyalty rewards, players can turn seasonal promotions into genuine value. Remember, bonuses are tools—not guarantees—and responsible play remains the cornerstone of any winning strategy. Use the playbook outlined above, track your results, and let each spin enhance both your skill set and your enjoyment of live dealer games and real‑money casino action. Happy Easter, and may your bets be as bright as the spring sunrise.
A trader holds a fractured position across multiple liquidity pools on BNB Smart Chain: some capital locked in a high-fee pool pair, other assets scattered across Ethereum and Polygon through bridged tokens, and exposure to a liquidation event that could trigger in the next block. Moving funds between pools normally requires outlay, slippage across multiple swaps, and time. Flash loans eliminate that constraint. Within a single atomic transaction, a trader can borrow unlimited capital, execute dozens of swaps or rebalancing moves, and repay the loan plus a small fee—all within the same block, with no risk of default because the transaction reverts if repayment fails.
The mechanics sound abstract, but the application is concrete. A sophisticated trader can use a flash loan to escape an underwater position without waiting for market recovery, to arbitrage price discrepancies across PancakeSwap’s multichain presence, or to liquidate a competitor’s collateral and capture the reward. The barrier is not capital but knowledge: understanding how to structure the transaction, which automated market maker pools offer flash loan infrastructure, where MEV extraction opportunities hide, and how to avoid the signature pitfall of flash loan strategies—building a complex transaction that fails at the last moment, wasting gas and revealing intent to competitors.

Flash loan mechanics on BNB Smart Chain and cross-chain liquidity pools
A flash loan is a lending primitive that operates within a single block and enforces repayment through transaction atomicity. On BNB Smart Chain, PancakeSwap’s liquidity pools expose a flashLoan function that allows a smart contract to borrow any amount of a token pair, provided the loan is repaid (plus a 0.05% fee on most pairs) before the transaction completes. If repayment fails, the entire transaction reverts—no partial execution, no debt carried forward. This guarantee is what makes flash loans risk-free for the lender and why no collateral is required.
The flow operates in three stages. First, the smart contract calls the flash loan function, specifying the amount and the token. The pool immediately transfers the borrowed amount to the contract. Second, the contract executes arbitrary logic: swaps, transfers, yield farming, or complex DeFi interactions. Third, the contract must call the repayment hook and transfer the original amount plus the fee back to the pool. If any step fails—insufficient balance, a reverted swap, or a missing repayment—the entire transaction unwinds. This means a trader can prototype high-complexity strategies with only the cost of gas and the flash fee, avoiding catastrophic loss of capital.
Cross-chain opportunities add another dimension. BNB Smart Chain, Ethereum, Polygon, and Solana each support DeFi applications, and liquidity of the same token can trade at different prices across chains. A flash loan on BNB Smart Chain cannot directly access Ethereum pools, but a sophisticated contract can use bridging protocols or cross-chain messaging to move liquidity atomically. The latency and cost of cross-chain operations are higher than single-chain flash loans, yet the mathematics can still favor the trade if price discrepancies are wide enough. A trader might flash loan USDC on BNB Smart Chain, swap it for a less liquid token, bridge the token to Ethereum, sell at a higher price, bridge the proceeds back, and repay—all within a single macro transaction if the infrastructure supports it.
Arbitrage structures: Exploiting price discrepancies between liquidity pools
The simplest flash loan strategy is triangular arbitrage. Suppose USDC trades at a slight premium to BUSD on one PancakeSwap pool but a discount on another. A flash loan enables a trader to borrow USDC, swap it for BUSD at the discounted rate, sell the BUSD for USDC at the premium, and pocket the difference. The capital never leaves the contract, and the profitable path is certain before execution. Gas costs and slippage reduce the profit margin, but on high-liquidity pairs where the constant product formula creates measurable mispricings, the edge can exceed transaction costs.
More complex structures involve multiple token hops and conditional logic. A trader might observe that ETH is overpriced relative to BTC on PancakeSwap but underpriced on a different pool pair. Using a flash loan, the trader borrows ETH, sells for BTC at the favorable rate, exchanges the BTC for ETH at the other pool at a higher ratio, and repays. This works if liquidity is sufficient and slippage does not erode the profit. The critical insight is that PancakeSwap’s automated market maker model (constant product formula) means every large swap moves the price, so the trader must account for mid-trade slippage and verify that the final proceeds exceed the flash fee plus gas.
The profitability calculation requires precision. If the flash fee is 0.05%, gas costs 5 USDC equivalent, and the arbitrage spread is 0.02%, a trader needs at least 25,000 USDC of liquidity in each pool for the numbers to work. Below that threshold, transaction costs exceed the spread. Above it, the strategy scales—a 500,000 USDC flash loan can generate meaningful profit if the execution is flawless. Sophisticated traders use private simulations or transaction builders to test the exact path before broadcasting, avoiding gas waste on failed strategies.
Liquidation capture through flash loan collateral
Lending protocols built on BNB Smart Chain (such as Venus or other margin lending systems) allow users to deposit collateral and borrow against it. If the price of the collateral falls relative to the borrowed amount, the position becomes undercollateralized and subject to liquidation. A liquidator can repay the debt and seize the collateral at a discount, typically 5–15% below market price. This discount is the incentive, but it requires holding the repayment asset in advance.
Flash loans unlock liquidations for traders without pre-positioned capital. Suppose a borrower on Venus has 100 ETH collateral and 50 USDC debt, and ETH’s price drops such that the liquidation threshold is breached. A liquidation bot would normally need 50 USDC in hand to repay the debt and claim the 100 ETH collateral. With a flash loan, the bot borrows 50 USDC, repays the debt, claims the 100 ETH, sells it for USDC, repays the 50 USDC plus the flash fee, and pockets the remainder—all in one transaction. The profitable gap between collateral value and debt plus liquidation fee funds the entire operation.
The MEV implications are significant. Liquidations are publicly observable; as soon as a position enters liquidation territory, competing bots detect it. Miners and validators can reorder transactions to favor their own liquidation bots or accept bribes. Flash loans reduce the entry barrier for liquidation participation, so the competition is fiercer and the MEV extraction more distributed. A well-capitalized liquidator using flash loans might capture liquidations faster than a traditional bot holding capital, but gas price competition and transaction ordering effects mean that flash loan liquidations are not guaranteed profit—they are competitive play in a public game.
Risk vectors: Gas costs, execution failures, and MEV sandwich attacks
Flash loans eliminate capital risk but introduce execution risk. A complex flash loan transaction that fails in any step—a calculation error, an insufficient balance after a swap, an expired oracle price—causes the entire transaction to revert. The trader loses only the gas cost, not the principal, but gas on BNB Smart Chain can still be substantial for multi-step transactions. A failed liquidation attempt might cost 1–5 USDC in wasted gas if the transaction is large enough or the network is congested. For low-margin strategies, this is enough to wipe out expected profit.
Sandwich attacks present a second vector. Because flash loan transactions are broadcast publicly in the mempool before execution, competing MEV actors can observe the transaction and insert their own transactions before or after it. A liquidation bot’s flash loan transaction might be observed, and a front-running actor could execute an identical liquidation with higher gas price, securing the collateral first. This is MEV extraction in its clearest form: the value of the liquidation is known and observable, so actors race to capture it. Real-time portfolio analytics on PancakeSwap can help identify vulnerable positions, but the race to liquidate them is unforgiving.
Price impact and slippage are a third consideration. If a flash loan strategy requires swapping a large amount relative to pool liquidity, the constant product formula will move the price significantly within the transaction. A trader must account for this by simulating the exact execution path, using tools such as Uniswap V2-style swap simulators or building the transaction in a private mempool. Broadcasting a transaction that miscalculates slippage exposes the intent and wastes gas; simulating it first and executing only if the math holds is the professional approach.
Structuring multi-pool and cross-chain flash loan transactions
A single flash loan from one pool is relatively straightforward, but traders often need capital from multiple sources. PancakeSwap offers flash loans on both BNB Smart Chain and other EVM-compatible chains like Ethereum, Polygon, and Base. A trader can use a router contract to request flash loans from multiple pools simultaneously, execute complex swaps across them, and repay all loans in a single transaction. The contract must encode the repayment obligation for each loan, manage the token flows, and ensure that each repayment is settled before the transaction ends.
Solidity libraries such as OpenZeppelin’s FlashLoanReceiver provide templates, but custom implementations are common. The key is to segregate logic: borrow all flash amounts, execute the strategy, calculate final balances, approve repayments, and execute the callback. If the strategy fails at any intermediate step, the fallback is to revert and lose only gas. If it succeeds, the profit flows to the contract owner (typically after a withdrawal function is called).
Cross-chain strategies complicate this further. If a trader wants to use a flash loan on BNB Smart Chain to exploit prices on Polygon, the contract must use a bridge. Bridges introduce latency and cost—typically 0.1–0.5% plus gas on each side. The arbitrage spread must exceed this overhead, and the execution must occur before the bridge messages are finalized. Many traders avoid true cross-chain flash loans for this reason, instead using flash loans to rebalance positions within a single chain, then handling cross-chain movement separately.
Detection and mitigation: Why flash loans do not break DeFi
Early DeFi protocols were vulnerable to flash loan attacks because they used spot prices from a single AMM as the oracle for lending or liquidation decisions. An attacker could flash loan a large amount, swap it in the pool to artificially move the price, use that inflated price to overborrow or liquidate a competitor, and repay the flash loan—pocketing the difference. Protocols like bZx suffered high-profile attacks this way. However, the DeFi ecosystem has since adopted defenses.
The most common mitigation is time-weighted average prices (TWAP). Instead of using the spot price at block N, protocols sample prices across multiple blocks and average them. Because flash loans execute within a single block, they cannot manipulate TWAP oracles. PancakeSwap and most lending protocols now use TWAP or Chainlink price feeds that incorporate data from multiple sources and time periods. This makes flash loan price manipulation ineffective for the attack vector it once enabled.
Another defense is explicit flash loan guards. Some protocols whitelist flash loan sources or require that borrowed funds come from specific addresses. Others use checks such as verifying that the contract’s balance at the end of the transaction is at least as high as it was at the start, preventing the use of flash loans to drain funds. These are protocol-level defenses, not perfect but sufficient to deter most straightforward attacks.
The professional takeaway is that flash loans enable legitimate trading strategies—arbitrage, liquidation, rebalancing—but they do not undermine protocol security if protocols use robust price feeds. A trader can get started with flash loan strategies by writing a smart contract, testing it on a testnet, simulating execution, and then deploying on mainnet once the math is verified. The flash loan itself is the tool; the strategy determines whether it generates profit or loss.
Practical economics: Calculating break-even and expected value
A flash loan strategy is profitable only if the captured value exceeds all costs. For a simple arbitrage, the costs are the flash fee (typically 0.05%), gas (2–10 USDC equivalent depending on transaction complexity and network congestion), and slippage (the difference between the quoted and actual prices as the swaps execute). The captured value is the price difference between the two pools, minus these costs.
Example: A trader observes USDC trading at 1.002 BUSD on Pool A but only 0.998 BUSD on Pool B. The 0.4% spread is attractive, but the flash fee (0.05%) and estimated gas (0.1%) total 0.15%, leaving 0.25% profit on a 1 million USDC trade—2,500 USDC. However, if Pool B has thin liquidity and the 1 million USDC swap moves the price 0.3%, the realized spread narrows to 0.1%, reducing profit to 1,000 USDC. If gas prices spike and the transaction costs 2,000 USDC in reality, the trade loses money despite the initial spread.
Professional traders use off-chain simulations to calculate expected value before broadcasting. They build the transaction locally, estimate gas using real network conditions, simulate the exact swap outputs using the pool’s constant product formula, and only execute if the expected profit exceeds a threshold (typically 50% above the breakeven to account for variance and failed transactions). This discipline separates profitable flash loan traders from those who chase observable spreads without modeling execution costs.
For liquidations, the economics are similar but with an additional variable: the liquidation discount. A liquidation captures value equal to the discount (5–15% typically) minus the flash fee and gas. If a liquidation discount is 10% and costs are 0.2%, the net capture is 9.8%—scaled by the size of the liquidated position. A 100,000 USDC liquidation nets around 9,800 USDC in profit, but only if the liquidator’s transaction beats all competitors to the block and the MEV environment does not spike gas prices.
Building for the future: Automation and protocol integration
The frontier of flash loan strategies involves tighter integration with PancakeSwap’s broader ecosystem. As limit orders, perpetuals trading, and staking features mature, flash loans can be used to unlock new use cases. A trader might use a flash loan to instantly rebalance across yield farming positions, ensuring optimal APR allocation without waiting for pool movements. Another might use flash loans to execute leveraged trades on perpetuals by borrowing capital, opening a large position, and closing it for profit—all within one transaction.
The infrastructure for this is still developing. Most sophisticated traders write custom smart contracts for each strategy because general-purpose flash loan routers do not yet capture all the nuanced logic. As the ecosystem matures and standardized flash loan frameworks improve, we can expect templates and libraries that make complex strategies more accessible. For now, the advantage goes to teams that understand both the token mechanics (swaps, pools, fees) and the smart contract execution model well enough to code custom solutions.
The deeper point is that flash loans represent a fundamental shift in DeFi capital efficiency. They eliminate the need to pre-position capital for trading strategies, lowering the barrier to sophisticated market participation. A trader with only gas fees in hand can participate in liquidation capture or arbitrage that once required millions in working capital. This democratizes certain trading activities while also increasing competition and reducing profit margins. The traders who thrive are those who model execution carefully, automate repetitive checks, and move fast when opportunities appear.
Frequently asked questions
What is the flash loan fee on PancakeSwap, and who receives it?
The standard flash loan fee on PancakeSwap’s liquidity pools is 0.05% of the borrowed amount. This fee is paid at the time of repayment and flows to the liquidity pool, effectively distributed to all liquidity providers as a return on their stake. The fee is enforced at the smart contract level and cannot be negotiated; failure to pay it causes the transaction to revert.
Can flash loans be used to attack DeFi protocols that use PancakeSwap prices?
Modern DeFi protocols use time-weighted average prices (TWAP) or decentralized price feeds from sources like Chainlink rather than spot prices, making them resistant to flash loan price manipulation. Flash loans execute within a single block and cannot move TWAP oracles. However, protocols that rely on spot prices or single-block price samples remain vulnerable; this is a protocol design flaw, not a flash loan weakness.
Do I need to write smart contract code to use flash loans?
Yes, flash loans require smart contract logic. There is no UI button on PancakeSwap’s DEX app to trigger a flash loan; you must write a contract that calls the flashLoan function, executes your strategy, and repays the amount plus the fee. Most flash loan users deploy custom contracts on testnets first, simulate execution, and then deploy to mainnet. Solidity knowledge and understanding of the constant product formula are prerequisites.
A trader holds a fractured position across multiple liquidity pools on BNB Smart Chain: some capital locked in a high-fee pool pair, other assets scattered across Ethereum and Polygon through bridged tokens, and exposure to a liquidation event that could trigger in the next block. Moving funds between pools normally requires outlay, slippage across multiple swaps, and time. Flash loans eliminate that constraint. Within a single atomic transaction, a trader can borrow unlimited capital, execute dozens of swaps or rebalancing moves, and repay the loan plus a small fee—all within the same block, with no risk of default because the transaction reverts if repayment fails.
The mechanics sound abstract, but the application is concrete. A sophisticated trader can use a flash loan to escape an underwater position without waiting for market recovery, to arbitrage price discrepancies across PancakeSwap’s multichain presence, or to liquidate a competitor’s collateral and capture the reward. The barrier is not capital but knowledge: understanding how to structure the transaction, which automated market maker pools offer flash loan infrastructure, where MEV extraction opportunities hide, and how to avoid the signature pitfall of flash loan strategies—building a complex transaction that fails at the last moment, wasting gas and revealing intent to competitors.
Flash loan mechanics on BNB Smart Chain and cross-chain liquidity pools
A flash loan is a lending primitive that operates within a single block and enforces repayment through transaction atomicity. On BNB Smart Chain, PancakeSwap’s liquidity pools expose a flashLoan function that allows a smart contract to borrow any amount of a token pair, provided the loan is repaid (plus a 0.05% fee on most pairs) before the transaction completes. If repayment fails, the entire transaction reverts—no partial execution, no debt carried forward. This guarantee is what makes flash loans risk-free for the lender and why no collateral is required.
The flow operates in three stages. First, the smart contract calls the flash loan function, specifying the amount and the token. The pool immediately transfers the borrowed amount to the contract. Second, the contract executes arbitrary logic: swaps, transfers, yield farming, or complex DeFi interactions. Third, the contract must call the repayment hook and transfer the original amount plus the fee back to the pool. If any step fails—insufficient balance, a reverted swap, or a missing repayment—the entire transaction unwinds. This means a trader can prototype high-complexity strategies with only the cost of gas and the flash fee, avoiding catastrophic loss of capital.
Cross-chain opportunities add another dimension. BNB Smart Chain, Ethereum, Polygon, and Solana each support DeFi applications, and liquidity of the same token can trade at different prices across chains. A flash loan on BNB Smart Chain cannot directly access Ethereum pools, but a sophisticated contract can use bridging protocols or cross-chain messaging to move liquidity atomically. The latency and cost of cross-chain operations are higher than single-chain flash loans, yet the mathematics can still favor the trade if price discrepancies are wide enough. A trader might flash loan USDC on BNB Smart Chain, swap it for a less liquid token, bridge the token to Ethereum, sell at a higher price, bridge the proceeds back, and repay—all within a single macro transaction if the infrastructure supports it.
Arbitrage structures: Exploiting price discrepancies between liquidity pools
The simplest flash loan strategy is triangular arbitrage. Suppose USDC trades at a slight premium to BUSD on one PancakeSwap pool but a discount on another. A flash loan enables a trader to borrow USDC, swap it for BUSD at the discounted rate, sell the BUSD for USDC at the premium, and pocket the difference. The capital never leaves the contract, and the profitable path is certain before execution. Gas costs and slippage reduce the profit margin, but on high-liquidity pairs where the constant product formula creates measurable mispricings, the edge can exceed transaction costs.
More complex structures involve multiple token hops and conditional logic. A trader might observe that ETH is overpriced relative to BTC on PancakeSwap but underpriced on a different pool pair. Using a flash loan, the trader borrows ETH, sells for BTC at the favorable rate, exchanges the BTC for ETH at the other pool at a higher ratio, and repays. This works if liquidity is sufficient and slippage does not erode the profit. The critical insight is that PancakeSwap’s automated market maker model (constant product formula) means every large swap moves the price, so the trader must account for mid-trade slippage and verify that the final proceeds exceed the flash fee plus gas.
The profitability calculation requires precision. If the flash fee is 0.05%, gas costs 5 USDC equivalent, and the arbitrage spread is 0.02%, a trader needs at least 25,000 USDC of liquidity in each pool for the numbers to work. Below that threshold, transaction costs exceed the spread. Above it, the strategy scales—a 500,000 USDC flash loan can generate meaningful profit if the execution is flawless. Sophisticated traders use private simulations or transaction builders to test the exact path before broadcasting, avoiding gas waste on failed strategies.
Liquidation capture through flash loan collateral
Lending protocols built on BNB Smart Chain (such as Venus or other margin lending systems) allow users to deposit collateral and borrow against it. If the price of the collateral falls relative to the borrowed amount, the position becomes undercollateralized and subject to liquidation. A liquidator can repay the debt and seize the collateral at a discount, typically 5–15% below market price. This discount is the incentive, but it requires holding the repayment asset in advance.
Flash loans unlock liquidations for traders without pre-positioned capital. Suppose a borrower on Venus has 100 ETH collateral and 50 USDC debt, and ETH’s price drops such that the liquidation threshold is breached. A liquidation bot would normally need 50 USDC in hand to repay the debt and claim the 100 ETH collateral. With a flash loan, the bot borrows 50 USDC, repays the debt, claims the 100 ETH, sells it for USDC, repays the 50 USDC plus the flash fee, and pockets the remainder—all in one transaction. The profitable gap between collateral value and debt plus liquidation fee funds the entire operation.
The MEV implications are significant. Liquidations are publicly observable; as soon as a position enters liquidation territory, competing bots detect it. Miners and validators can reorder transactions to favor their own liquidation bots or accept bribes. Flash loans reduce the entry barrier for liquidation participation, so the competition is fiercer and the MEV extraction more distributed. A well-capitalized liquidator using flash loans might capture liquidations faster than a traditional bot holding capital, but gas price competition and transaction ordering effects mean that flash loan liquidations are not guaranteed profit—they are competitive play in a public game.
Risk vectors: Gas costs, execution failures, and MEV sandwich attacks
Flash loans eliminate capital risk but introduce execution risk. A complex flash loan transaction that fails in any step—a calculation error, an insufficient balance after a swap, an expired oracle price—causes the entire transaction to revert. The trader loses only the gas cost, not the principal, but gas on BNB Smart Chain can still be substantial for multi-step transactions. A failed liquidation attempt might cost 1–5 USDC in wasted gas if the transaction is large enough or the network is congested. For low-margin strategies, this is enough to wipe out expected profit.
Sandwich attacks present a second vector. Because flash loan transactions are broadcast publicly in the mempool before execution, competing MEV actors can observe the transaction and insert their own transactions before or after it. A liquidation bot’s flash loan transaction might be observed, and a front-running actor could execute an identical liquidation with higher gas price, securing the collateral first. This is MEV extraction in its clearest form: the value of the liquidation is known and observable, so actors race to capture it. Real-time portfolio analytics on PancakeSwap can help identify vulnerable positions, but the race to liquidate them is unforgiving.
Price impact and slippage are a third consideration. If a flash loan strategy requires swapping a large amount relative to pool liquidity, the constant product formula will move the price significantly within the transaction. A trader must account for this by simulating the exact execution path, using tools such as Uniswap V2-style swap simulators or building the transaction in a private mempool. Broadcasting a transaction that miscalculates slippage exposes the intent and wastes gas; simulating it first and executing only if the math holds is the professional approach.
Structuring multi-pool and cross-chain flash loan transactions
A single flash loan from one pool is relatively straightforward, but traders often need capital from multiple sources. PancakeSwap offers flash loans on both BNB Smart Chain and other EVM-compatible chains like Ethereum, Polygon, and Base. A trader can use a router contract to request flash loans from multiple pools simultaneously, execute complex swaps across them, and repay all loans in a single transaction. The contract must encode the repayment obligation for each loan, manage the token flows, and ensure that each repayment is settled before the transaction ends.
Solidity libraries such as OpenZeppelin’s FlashLoanReceiver provide templates, but custom implementations are common. The key is to segregate logic: borrow all flash amounts, execute the strategy, calculate final balances, approve repayments, and execute the callback. If the strategy fails at any intermediate step, the fallback is to revert and lose only gas. If it succeeds, the profit flows to the contract owner (typically after a withdrawal function is called).
Cross-chain strategies complicate this further. If a trader wants to use a flash loan on BNB Smart Chain to exploit prices on Polygon, the contract must use a bridge. Bridges introduce latency and cost—typically 0.1–0.5% plus gas on each side. The arbitrage spread must exceed this overhead, and the execution must occur before the bridge messages are finalized. Many traders avoid true cross-chain flash loans for this reason, instead using flash loans to rebalance positions within a single chain, then handling cross-chain movement separately.
Detection and mitigation: Why flash loans do not break DeFi
Early DeFi protocols were vulnerable to flash loan attacks because they used spot prices from a single AMM as the oracle for lending or liquidation decisions. An attacker could flash loan a large amount, swap it in the pool to artificially move the price, use that inflated price to overborrow or liquidate a competitor, and repay the flash loan—pocketing the difference. Protocols like bZx suffered high-profile attacks this way. However, the DeFi ecosystem has since adopted defenses.
The most common mitigation is time-weighted average prices (TWAP). Instead of using the spot price at block N, protocols sample prices across multiple blocks and average them. Because flash loans execute within a single block, they cannot manipulate TWAP oracles. PancakeSwap and most lending protocols now use TWAP or Chainlink price feeds that incorporate data from multiple sources and time periods. This makes flash loan price manipulation ineffective for the attack vector it once enabled.
Another defense is explicit flash loan guards. Some protocols whitelist flash loan sources or require that borrowed funds come from specific addresses. Others use checks such as verifying that the contract’s balance at the end of the transaction is at least as high as it was at the start, preventing the use of flash loans to drain funds. These are protocol-level defenses, not perfect but sufficient to deter most straightforward attacks.
The professional takeaway is that flash loans enable legitimate trading strategies—arbitrage, liquidation, rebalancing—but they do not undermine protocol security if protocols use robust price feeds. A trader can get started with flash loan strategies by writing a smart contract, testing it on a testnet, simulating execution, and then deploying on mainnet once the math is verified. The flash loan itself is the tool; the strategy determines whether it generates profit or loss.
Practical economics: Calculating break-even and expected value
A flash loan strategy is profitable only if the captured value exceeds all costs. For a simple arbitrage, the costs are the flash fee (typically 0.05%), gas (2–10 USDC equivalent depending on transaction complexity and network congestion), and slippage (the difference between the quoted and actual prices as the swaps execute). The captured value is the price difference between the two pools, minus these costs.
Example: A trader observes USDC trading at 1.002 BUSD on Pool A but only 0.998 BUSD on Pool B. The 0.4% spread is attractive, but the flash fee (0.05%) and estimated gas (0.1%) total 0.15%, leaving 0.25% profit on a 1 million USDC trade—2,500 USDC. However, if Pool B has thin liquidity and the 1 million USDC swap moves the price 0.3%, the realized spread narrows to 0.1%, reducing profit to 1,000 USDC. If gas prices spike and the transaction costs 2,000 USDC in reality, the trade loses money despite the initial spread.
Professional traders use off-chain simulations to calculate expected value before broadcasting. They build the transaction locally, estimate gas using real network conditions, simulate the exact swap outputs using the pool’s constant product formula, and only execute if the expected profit exceeds a threshold (typically 50% above the breakeven to account for variance and failed transactions). This discipline separates profitable flash loan traders from those who chase observable spreads without modeling execution costs.
For liquidations, the economics are similar but with an additional variable: the liquidation discount. A liquidation captures value equal to the discount (5–15% typically) minus the flash fee and gas. If a liquidation discount is 10% and costs are 0.2%, the net capture is 9.8%—scaled by the size of the liquidated position. A 100,000 USDC liquidation nets around 9,800 USDC in profit, but only if the liquidator’s transaction beats all competitors to the block and the MEV environment does not spike gas prices.
Building for the future: Automation and protocol integration
The frontier of flash loan strategies involves tighter integration with PancakeSwap’s broader ecosystem. As limit orders, perpetuals trading, and staking features mature, flash loans can be used to unlock new use cases. A trader might use a flash loan to instantly rebalance across yield farming positions, ensuring optimal APR allocation without waiting for pool movements. Another might use flash loans to execute leveraged trades on perpetuals by borrowing capital, opening a large position, and closing it for profit—all within one transaction.
The infrastructure for this is still developing. Most sophisticated traders write custom smart contracts for each strategy because general-purpose flash loan routers do not yet capture all the nuanced logic. As the ecosystem matures and standardized flash loan frameworks improve, we can expect templates and libraries that make complex strategies more accessible. For now, the advantage goes to teams that understand both the token mechanics (swaps, pools, fees) and the smart contract execution model well enough to code custom solutions.
The deeper point is that flash loans represent a fundamental shift in DeFi capital efficiency. They eliminate the need to pre-position capital for trading strategies, lowering the barrier to sophisticated market participation. A trader with only gas fees in hand can participate in liquidation capture or arbitrage that once required millions in working capital. This democratizes certain trading activities while also increasing competition and reducing profit margins. The traders who thrive are those who model execution carefully, automate repetitive checks, and move fast when opportunities appear.
Frequently asked questions
What is the flash loan fee on PancakeSwap, and who receives it?
The standard flash loan fee on PancakeSwap’s liquidity pools is 0.05% of the borrowed amount. This fee is paid at the time of repayment and flows to the liquidity pool, effectively distributed to all liquidity providers as a return on their stake. The fee is enforced at the smart contract level and cannot be negotiated; failure to pay it causes the transaction to revert.
Can flash loans be used to attack DeFi protocols that use PancakeSwap prices?
Modern DeFi protocols use time-weighted average prices (TWAP) or decentralized price feeds from sources like Chainlink rather than spot prices, making them resistant to flash loan price manipulation. Flash loans execute within a single block and cannot move TWAP oracles. However, protocols that rely on spot prices or single-block price samples remain vulnerable; this is a protocol design flaw, not a flash loan weakness.
Do I need to write smart contract code to use flash loans?
Yes, flash loans require smart contract logic. There is no UI button on PancakeSwap’s DEX app to trigger a flash loan; you must write a contract that calls the flashLoan function, executes your strategy, and repays the amount plus the fee. Most flash loan users deploy custom contracts on testnets first, simulate execution, and then deploy to mainnet. Solidity knowledge and understanding of the constant product formula are prerequisites.
A trader holds a fractured position across multiple liquidity pools on BNB Smart Chain: some capital locked in a high-fee pool pair, other assets scattered across Ethereum and Polygon through bridged tokens, and exposure to a liquidation event that could trigger in the next block. Moving funds between pools normally requires outlay, slippage across multiple swaps, and time. Flash loans eliminate that constraint. Within a single atomic transaction, a trader can borrow unlimited capital, execute dozens of swaps or rebalancing moves, and repay the loan plus a small fee—all within the same block, with no risk of default because the transaction reverts if repayment fails.
The mechanics sound abstract, but the application is concrete. A sophisticated trader can use a flash loan to escape an underwater position without waiting for market recovery, to arbitrage price discrepancies across PancakeSwap’s multichain presence, or to liquidate a competitor’s collateral and capture the reward. The barrier is not capital but knowledge: understanding how to structure the transaction, which automated market maker pools offer flash loan infrastructure, where MEV extraction opportunities hide, and how to avoid the signature pitfall of flash loan strategies—building a complex transaction that fails at the last moment, wasting gas and revealing intent to competitors.
Flash loan mechanics on BNB Smart Chain and cross-chain liquidity pools
A flash loan is a lending primitive that operates within a single block and enforces repayment through transaction atomicity. On BNB Smart Chain, PancakeSwap’s liquidity pools expose a flashLoan function that allows a smart contract to borrow any amount of a token pair, provided the loan is repaid (plus a 0.05% fee on most pairs) before the transaction completes. If repayment fails, the entire transaction reverts—no partial execution, no debt carried forward. This guarantee is what makes flash loans risk-free for the lender and why no collateral is required.
The flow operates in three stages. First, the smart contract calls the flash loan function, specifying the amount and the token. The pool immediately transfers the borrowed amount to the contract. Second, the contract executes arbitrary logic: swaps, transfers, yield farming, or complex DeFi interactions. Third, the contract must call the repayment hook and transfer the original amount plus the fee back to the pool. If any step fails—insufficient balance, a reverted swap, or a missing repayment—the entire transaction unwinds. This means a trader can prototype high-complexity strategies with only the cost of gas and the flash fee, avoiding catastrophic loss of capital.
Cross-chain opportunities add another dimension. BNB Smart Chain, Ethereum, Polygon, and Solana each support DeFi applications, and liquidity of the same token can trade at different prices across chains. A flash loan on BNB Smart Chain cannot directly access Ethereum pools, but a sophisticated contract can use bridging protocols or cross-chain messaging to move liquidity atomically. The latency and cost of cross-chain operations are higher than single-chain flash loans, yet the mathematics can still favor the trade if price discrepancies are wide enough. A trader might flash loan USDC on BNB Smart Chain, swap it for a less liquid token, bridge the token to Ethereum, sell at a higher price, bridge the proceeds back, and repay—all within a single macro transaction if the infrastructure supports it.
Arbitrage structures: Exploiting price discrepancies between liquidity pools
The simplest flash loan strategy is triangular arbitrage. Suppose USDC trades at a slight premium to BUSD on one PancakeSwap pool but a discount on another. A flash loan enables a trader to borrow USDC, swap it for BUSD at the discounted rate, sell the BUSD for USDC at the premium, and pocket the difference. The capital never leaves the contract, and the profitable path is certain before execution. Gas costs and slippage reduce the profit margin, but on high-liquidity pairs where the constant product formula creates measurable mispricings, the edge can exceed transaction costs.
More complex structures involve multiple token hops and conditional logic. A trader might observe that ETH is overpriced relative to BTC on PancakeSwap but underpriced on a different pool pair. Using a flash loan, the trader borrows ETH, sells for BTC at the favorable rate, exchanges the BTC for ETH at the other pool at a higher ratio, and repays. This works if liquidity is sufficient and slippage does not erode the profit. The critical insight is that PancakeSwap’s automated market maker model (constant product formula) means every large swap moves the price, so the trader must account for mid-trade slippage and verify that the final proceeds exceed the flash fee plus gas.
The profitability calculation requires precision. If the flash fee is 0.05%, gas costs 5 USDC equivalent, and the arbitrage spread is 0.02%, a trader needs at least 25,000 USDC of liquidity in each pool for the numbers to work. Below that threshold, transaction costs exceed the spread. Above it, the strategy scales—a 500,000 USDC flash loan can generate meaningful profit if the execution is flawless. Sophisticated traders use private simulations or transaction builders to test the exact path before broadcasting, avoiding gas waste on failed strategies.
Liquidation capture through flash loan collateral
Lending protocols built on BNB Smart Chain (such as Venus or other margin lending systems) allow users to deposit collateral and borrow against it. If the price of the collateral falls relative to the borrowed amount, the position becomes undercollateralized and subject to liquidation. A liquidator can repay the debt and seize the collateral at a discount, typically 5–15% below market price. This discount is the incentive, but it requires holding the repayment asset in advance.
Flash loans unlock liquidations for traders without pre-positioned capital. Suppose a borrower on Venus has 100 ETH collateral and 50 USDC debt, and ETH’s price drops such that the liquidation threshold is breached. A liquidation bot would normally need 50 USDC in hand to repay the debt and claim the 100 ETH collateral. With a flash loan, the bot borrows 50 USDC, repays the debt, claims the 100 ETH, sells it for USDC, repays the 50 USDC plus the flash fee, and pockets the remainder—all in one transaction. The profitable gap between collateral value and debt plus liquidation fee funds the entire operation.
The MEV implications are significant. Liquidations are publicly observable; as soon as a position enters liquidation territory, competing bots detect it. Miners and validators can reorder transactions to favor their own liquidation bots or accept bribes. Flash loans reduce the entry barrier for liquidation participation, so the competition is fiercer and the MEV extraction more distributed. A well-capitalized liquidator using flash loans might capture liquidations faster than a traditional bot holding capital, but gas price competition and transaction ordering effects mean that flash loan liquidations are not guaranteed profit—they are competitive play in a public game.
Risk vectors: Gas costs, execution failures, and MEV sandwich attacks
Flash loans eliminate capital risk but introduce execution risk. A complex flash loan transaction that fails in any step—a calculation error, an insufficient balance after a swap, an expired oracle price—causes the entire transaction to revert. The trader loses only the gas cost, not the principal, but gas on BNB Smart Chain can still be substantial for multi-step transactions. A failed liquidation attempt might cost 1–5 USDC in wasted gas if the transaction is large enough or the network is congested. For low-margin strategies, this is enough to wipe out expected profit.
Sandwich attacks present a second vector. Because flash loan transactions are broadcast publicly in the mempool before execution, competing MEV actors can observe the transaction and insert their own transactions before or after it. A liquidation bot’s flash loan transaction might be observed, and a front-running actor could execute an identical liquidation with higher gas price, securing the collateral first. This is MEV extraction in its clearest form: the value of the liquidation is known and observable, so actors race to capture it. Real-time portfolio analytics on PancakeSwap can help identify vulnerable positions, but the race to liquidate them is unforgiving.
Price impact and slippage are a third consideration. If a flash loan strategy requires swapping a large amount relative to pool liquidity, the constant product formula will move the price significantly within the transaction. A trader must account for this by simulating the exact execution path, using tools such as Uniswap V2-style swap simulators or building the transaction in a private mempool. Broadcasting a transaction that miscalculates slippage exposes the intent and wastes gas; simulating it first and executing only if the math holds is the professional approach.
Structuring multi-pool and cross-chain flash loan transactions
A single flash loan from one pool is relatively straightforward, but traders often need capital from multiple sources. PancakeSwap offers flash loans on both BNB Smart Chain and other EVM-compatible chains like Ethereum, Polygon, and Base. A trader can use a router contract to request flash loans from multiple pools simultaneously, execute complex swaps across them, and repay all loans in a single transaction. The contract must encode the repayment obligation for each loan, manage the token flows, and ensure that each repayment is settled before the transaction ends.
Solidity libraries such as OpenZeppelin’s FlashLoanReceiver provide templates, but custom implementations are common. The key is to segregate logic: borrow all flash amounts, execute the strategy, calculate final balances, approve repayments, and execute the callback. If the strategy fails at any intermediate step, the fallback is to revert and lose only gas. If it succeeds, the profit flows to the contract owner (typically after a withdrawal function is called).
Cross-chain strategies complicate this further. If a trader wants to use a flash loan on BNB Smart Chain to exploit prices on Polygon, the contract must use a bridge. Bridges introduce latency and cost—typically 0.1–0.5% plus gas on each side. The arbitrage spread must exceed this overhead, and the execution must occur before the bridge messages are finalized. Many traders avoid true cross-chain flash loans for this reason, instead using flash loans to rebalance positions within a single chain, then handling cross-chain movement separately.
Detection and mitigation: Why flash loans do not break DeFi
Early DeFi protocols were vulnerable to flash loan attacks because they used spot prices from a single AMM as the oracle for lending or liquidation decisions. An attacker could flash loan a large amount, swap it in the pool to artificially move the price, use that inflated price to overborrow or liquidate a competitor, and repay the flash loan—pocketing the difference. Protocols like bZx suffered high-profile attacks this way. However, the DeFi ecosystem has since adopted defenses.
The most common mitigation is time-weighted average prices (TWAP). Instead of using the spot price at block N, protocols sample prices across multiple blocks and average them. Because flash loans execute within a single block, they cannot manipulate TWAP oracles. PancakeSwap and most lending protocols now use TWAP or Chainlink price feeds that incorporate data from multiple sources and time periods. This makes flash loan price manipulation ineffective for the attack vector it once enabled.
Another defense is explicit flash loan guards. Some protocols whitelist flash loan sources or require that borrowed funds come from specific addresses. Others use checks such as verifying that the contract’s balance at the end of the transaction is at least as high as it was at the start, preventing the use of flash loans to drain funds. These are protocol-level defenses, not perfect but sufficient to deter most straightforward attacks.
The professional takeaway is that flash loans enable legitimate trading strategies—arbitrage, liquidation, rebalancing—but they do not undermine protocol security if protocols use robust price feeds. A trader can get started with flash loan strategies by writing a smart contract, testing it on a testnet, simulating execution, and then deploying on mainnet once the math is verified. The flash loan itself is the tool; the strategy determines whether it generates profit or loss.
Practical economics: Calculating break-even and expected value
A flash loan strategy is profitable only if the captured value exceeds all costs. For a simple arbitrage, the costs are the flash fee (typically 0.05%), gas (2–10 USDC equivalent depending on transaction complexity and network congestion), and slippage (the difference between the quoted and actual prices as the swaps execute). The captured value is the price difference between the two pools, minus these costs.
Example: A trader observes USDC trading at 1.002 BUSD on Pool A but only 0.998 BUSD on Pool B. The 0.4% spread is attractive, but the flash fee (0.05%) and estimated gas (0.1%) total 0.15%, leaving 0.25% profit on a 1 million USDC trade—2,500 USDC. However, if Pool B has thin liquidity and the 1 million USDC swap moves the price 0.3%, the realized spread narrows to 0.1%, reducing profit to 1,000 USDC. If gas prices spike and the transaction costs 2,000 USDC in reality, the trade loses money despite the initial spread.
Professional traders use off-chain simulations to calculate expected value before broadcasting. They build the transaction locally, estimate gas using real network conditions, simulate the exact swap outputs using the pool’s constant product formula, and only execute if the expected profit exceeds a threshold (typically 50% above the breakeven to account for variance and failed transactions). This discipline separates profitable flash loan traders from those who chase observable spreads without modeling execution costs.
For liquidations, the economics are similar but with an additional variable: the liquidation discount. A liquidation captures value equal to the discount (5–15% typically) minus the flash fee and gas. If a liquidation discount is 10% and costs are 0.2%, the net capture is 9.8%—scaled by the size of the liquidated position. A 100,000 USDC liquidation nets around 9,800 USDC in profit, but only if the liquidator’s transaction beats all competitors to the block and the MEV environment does not spike gas prices.
Building for the future: Automation and protocol integration
The frontier of flash loan strategies involves tighter integration with PancakeSwap’s broader ecosystem. As limit orders, perpetuals trading, and staking features mature, flash loans can be used to unlock new use cases. A trader might use a flash loan to instantly rebalance across yield farming positions, ensuring optimal APR allocation without waiting for pool movements. Another might use flash loans to execute leveraged trades on perpetuals by borrowing capital, opening a large position, and closing it for profit—all within one transaction.
The infrastructure for this is still developing. Most sophisticated traders write custom smart contracts for each strategy because general-purpose flash loan routers do not yet capture all the nuanced logic. As the ecosystem matures and standardized flash loan frameworks improve, we can expect templates and libraries that make complex strategies more accessible. For now, the advantage goes to teams that understand both the token mechanics (swaps, pools, fees) and the smart contract execution model well enough to code custom solutions.
The deeper point is that flash loans represent a fundamental shift in DeFi capital efficiency. They eliminate the need to pre-position capital for trading strategies, lowering the barrier to sophisticated market participation. A trader with only gas fees in hand can participate in liquidation capture or arbitrage that once required millions in working capital. This democratizes certain trading activities while also increasing competition and reducing profit margins. The traders who thrive are those who model execution carefully, automate repetitive checks, and move fast when opportunities appear.
Frequently asked questions
What is the flash loan fee on PancakeSwap, and who receives it?
The standard flash loan fee on PancakeSwap’s liquidity pools is 0.05% of the borrowed amount. This fee is paid at the time of repayment and flows to the liquidity pool, effectively distributed to all liquidity providers as a return on their stake. The fee is enforced at the smart contract level and cannot be negotiated; failure to pay it causes the transaction to revert.
Can flash loans be used to attack DeFi protocols that use PancakeSwap prices?
Modern DeFi protocols use time-weighted average prices (TWAP) or decentralized price feeds from sources like Chainlink rather than spot prices, making them resistant to flash loan price manipulation. Flash loans execute within a single block and cannot move TWAP oracles. However, protocols that rely on spot prices or single-block price samples remain vulnerable; this is a protocol design flaw, not a flash loan weakness.
Do I need to write smart contract code to use flash loans?
Yes, flash loans require smart contract logic. There is no UI button on PancakeSwap’s DEX app to trigger a flash loan; you must write a contract that calls the flashLoan function, executes your strategy, and repays the amount plus the fee. Most flash loan users deploy custom contracts on testnets first, simulate execution, and then deploy to mainnet. Solidity knowledge and understanding of the constant product formula are prerequisites.
A trader holds a fractured position across multiple liquidity pools on BNB Smart Chain: some capital locked in a high-fee pool pair, other assets scattered across Ethereum and Polygon through bridged tokens, and exposure to a liquidation event that could trigger in the next block. Moving funds between pools normally requires outlay, slippage across multiple swaps, and time. Flash loans eliminate that constraint. Within a single atomic transaction, a trader can borrow unlimited capital, execute dozens of swaps or rebalancing moves, and repay the loan plus a small fee—all within the same block, with no risk of default because the transaction reverts if repayment fails.
The mechanics sound abstract, but the application is concrete. A sophisticated trader can use a flash loan to escape an underwater position without waiting for market recovery, to arbitrage price discrepancies across PancakeSwap’s multichain presence, or to liquidate a competitor’s collateral and capture the reward. The barrier is not capital but knowledge: understanding how to structure the transaction, which automated market maker pools offer flash loan infrastructure, where MEV extraction opportunities hide, and how to avoid the signature pitfall of flash loan strategies—building a complex transaction that fails at the last moment, wasting gas and revealing intent to competitors.
Flash loan mechanics on BNB Smart Chain and cross-chain liquidity pools
A flash loan is a lending primitive that operates within a single block and enforces repayment through transaction atomicity. On BNB Smart Chain, PancakeSwap’s liquidity pools expose a flashLoan function that allows a smart contract to borrow any amount of a token pair, provided the loan is repaid (plus a 0.05% fee on most pairs) before the transaction completes. If repayment fails, the entire transaction reverts—no partial execution, no debt carried forward. This guarantee is what makes flash loans risk-free for the lender and why no collateral is required.
The flow operates in three stages. First, the smart contract calls the flash loan function, specifying the amount and the token. The pool immediately transfers the borrowed amount to the contract. Second, the contract executes arbitrary logic: swaps, transfers, yield farming, or complex DeFi interactions. Third, the contract must call the repayment hook and transfer the original amount plus the fee back to the pool. If any step fails—insufficient balance, a reverted swap, or a missing repayment—the entire transaction unwinds. This means a trader can prototype high-complexity strategies with only the cost of gas and the flash fee, avoiding catastrophic loss of capital.
Cross-chain opportunities add another dimension. BNB Smart Chain, Ethereum, Polygon, and Solana each support DeFi applications, and liquidity of the same token can trade at different prices across chains. A flash loan on BNB Smart Chain cannot directly access Ethereum pools, but a sophisticated contract can use bridging protocols or cross-chain messaging to move liquidity atomically. The latency and cost of cross-chain operations are higher than single-chain flash loans, yet the mathematics can still favor the trade if price discrepancies are wide enough. A trader might flash loan USDC on BNB Smart Chain, swap it for a less liquid token, bridge the token to Ethereum, sell at a higher price, bridge the proceeds back, and repay—all within a single macro transaction if the infrastructure supports it.
Arbitrage structures: Exploiting price discrepancies between liquidity pools
The simplest flash loan strategy is triangular arbitrage. Suppose USDC trades at a slight premium to BUSD on one PancakeSwap pool but a discount on another. A flash loan enables a trader to borrow USDC, swap it for BUSD at the discounted rate, sell the BUSD for USDC at the premium, and pocket the difference. The capital never leaves the contract, and the profitable path is certain before execution. Gas costs and slippage reduce the profit margin, but on high-liquidity pairs where the constant product formula creates measurable mispricings, the edge can exceed transaction costs.
More complex structures involve multiple token hops and conditional logic. A trader might observe that ETH is overpriced relative to BTC on PancakeSwap but underpriced on a different pool pair. Using a flash loan, the trader borrows ETH, sells for BTC at the favorable rate, exchanges the BTC for ETH at the other pool at a higher ratio, and repays. This works if liquidity is sufficient and slippage does not erode the profit. The critical insight is that PancakeSwap’s automated market maker model (constant product formula) means every large swap moves the price, so the trader must account for mid-trade slippage and verify that the final proceeds exceed the flash fee plus gas.
The profitability calculation requires precision. If the flash fee is 0.05%, gas costs 5 USDC equivalent, and the arbitrage spread is 0.02%, a trader needs at least 25,000 USDC of liquidity in each pool for the numbers to work. Below that threshold, transaction costs exceed the spread. Above it, the strategy scales—a 500,000 USDC flash loan can generate meaningful profit if the execution is flawless. Sophisticated traders use private simulations or transaction builders to test the exact path before broadcasting, avoiding gas waste on failed strategies.
Liquidation capture through flash loan collateral
Lending protocols built on BNB Smart Chain (such as Venus or other margin lending systems) allow users to deposit collateral and borrow against it. If the price of the collateral falls relative to the borrowed amount, the position becomes undercollateralized and subject to liquidation. A liquidator can repay the debt and seize the collateral at a discount, typically 5–15% below market price. This discount is the incentive, but it requires holding the repayment asset in advance.
Flash loans unlock liquidations for traders without pre-positioned capital. Suppose a borrower on Venus has 100 ETH collateral and 50 USDC debt, and ETH’s price drops such that the liquidation threshold is breached. A liquidation bot would normally need 50 USDC in hand to repay the debt and claim the 100 ETH collateral. With a flash loan, the bot borrows 50 USDC, repays the debt, claims the 100 ETH, sells it for USDC, repays the 50 USDC plus the flash fee, and pockets the remainder—all in one transaction. The profitable gap between collateral value and debt plus liquidation fee funds the entire operation.
The MEV implications are significant. Liquidations are publicly observable; as soon as a position enters liquidation territory, competing bots detect it. Miners and validators can reorder transactions to favor their own liquidation bots or accept bribes. Flash loans reduce the entry barrier for liquidation participation, so the competition is fiercer and the MEV extraction more distributed. A well-capitalized liquidator using flash loans might capture liquidations faster than a traditional bot holding capital, but gas price competition and transaction ordering effects mean that flash loan liquidations are not guaranteed profit—they are competitive play in a public game.
Risk vectors: Gas costs, execution failures, and MEV sandwich attacks
Flash loans eliminate capital risk but introduce execution risk. A complex flash loan transaction that fails in any step—a calculation error, an insufficient balance after a swap, an expired oracle price—causes the entire transaction to revert. The trader loses only the gas cost, not the principal, but gas on BNB Smart Chain can still be substantial for multi-step transactions. A failed liquidation attempt might cost 1–5 USDC in wasted gas if the transaction is large enough or the network is congested. For low-margin strategies, this is enough to wipe out expected profit.
Sandwich attacks present a second vector. Because flash loan transactions are broadcast publicly in the mempool before execution, competing MEV actors can observe the transaction and insert their own transactions before or after it. A liquidation bot’s flash loan transaction might be observed, and a front-running actor could execute an identical liquidation with higher gas price, securing the collateral first. This is MEV extraction in its clearest form: the value of the liquidation is known and observable, so actors race to capture it. Real-time portfolio analytics on PancakeSwap can help identify vulnerable positions, but the race to liquidate them is unforgiving.
Price impact and slippage are a third consideration. If a flash loan strategy requires swapping a large amount relative to pool liquidity, the constant product formula will move the price significantly within the transaction. A trader must account for this by simulating the exact execution path, using tools such as Uniswap V2-style swap simulators or building the transaction in a private mempool. Broadcasting a transaction that miscalculates slippage exposes the intent and wastes gas; simulating it first and executing only if the math holds is the professional approach.
Structuring multi-pool and cross-chain flash loan transactions
A single flash loan from one pool is relatively straightforward, but traders often need capital from multiple sources. PancakeSwap offers flash loans on both BNB Smart Chain and other EVM-compatible chains like Ethereum, Polygon, and Base. A trader can use a router contract to request flash loans from multiple pools simultaneously, execute complex swaps across them, and repay all loans in a single transaction. The contract must encode the repayment obligation for each loan, manage the token flows, and ensure that each repayment is settled before the transaction ends.
Solidity libraries such as OpenZeppelin’s FlashLoanReceiver provide templates, but custom implementations are common. The key is to segregate logic: borrow all flash amounts, execute the strategy, calculate final balances, approve repayments, and execute the callback. If the strategy fails at any intermediate step, the fallback is to revert and lose only gas. If it succeeds, the profit flows to the contract owner (typically after a withdrawal function is called).
Cross-chain strategies complicate this further. If a trader wants to use a flash loan on BNB Smart Chain to exploit prices on Polygon, the contract must use a bridge. Bridges introduce latency and cost—typically 0.1–0.5% plus gas on each side. The arbitrage spread must exceed this overhead, and the execution must occur before the bridge messages are finalized. Many traders avoid true cross-chain flash loans for this reason, instead using flash loans to rebalance positions within a single chain, then handling cross-chain movement separately.
Detection and mitigation: Why flash loans do not break DeFi
Early DeFi protocols were vulnerable to flash loan attacks because they used spot prices from a single AMM as the oracle for lending or liquidation decisions. An attacker could flash loan a large amount, swap it in the pool to artificially move the price, use that inflated price to overborrow or liquidate a competitor, and repay the flash loan—pocketing the difference. Protocols like bZx suffered high-profile attacks this way. However, the DeFi ecosystem has since adopted defenses.
The most common mitigation is time-weighted average prices (TWAP). Instead of using the spot price at block N, protocols sample prices across multiple blocks and average them. Because flash loans execute within a single block, they cannot manipulate TWAP oracles. PancakeSwap and most lending protocols now use TWAP or Chainlink price feeds that incorporate data from multiple sources and time periods. This makes flash loan price manipulation ineffective for the attack vector it once enabled.
Another defense is explicit flash loan guards. Some protocols whitelist flash loan sources or require that borrowed funds come from specific addresses. Others use checks such as verifying that the contract’s balance at the end of the transaction is at least as high as it was at the start, preventing the use of flash loans to drain funds. These are protocol-level defenses, not perfect but sufficient to deter most straightforward attacks.
The professional takeaway is that flash loans enable legitimate trading strategies—arbitrage, liquidation, rebalancing—but they do not undermine protocol security if protocols use robust price feeds. A trader can get started with flash loan strategies by writing a smart contract, testing it on a testnet, simulating execution, and then deploying on mainnet once the math is verified. The flash loan itself is the tool; the strategy determines whether it generates profit or loss.
Practical economics: Calculating break-even and expected value
A flash loan strategy is profitable only if the captured value exceeds all costs. For a simple arbitrage, the costs are the flash fee (typically 0.05%), gas (2–10 USDC equivalent depending on transaction complexity and network congestion), and slippage (the difference between the quoted and actual prices as the swaps execute). The captured value is the price difference between the two pools, minus these costs.
Example: A trader observes USDC trading at 1.002 BUSD on Pool A but only 0.998 BUSD on Pool B. The 0.4% spread is attractive, but the flash fee (0.05%) and estimated gas (0.1%) total 0.15%, leaving 0.25% profit on a 1 million USDC trade—2,500 USDC. However, if Pool B has thin liquidity and the 1 million USDC swap moves the price 0.3%, the realized spread narrows to 0.1%, reducing profit to 1,000 USDC. If gas prices spike and the transaction costs 2,000 USDC in reality, the trade loses money despite the initial spread.
Professional traders use off-chain simulations to calculate expected value before broadcasting. They build the transaction locally, estimate gas using real network conditions, simulate the exact swap outputs using the pool’s constant product formula, and only execute if the expected profit exceeds a threshold (typically 50% above the breakeven to account for variance and failed transactions). This discipline separates profitable flash loan traders from those who chase observable spreads without modeling execution costs.
For liquidations, the economics are similar but with an additional variable: the liquidation discount. A liquidation captures value equal to the discount (5–15% typically) minus the flash fee and gas. If a liquidation discount is 10% and costs are 0.2%, the net capture is 9.8%—scaled by the size of the liquidated position. A 100,000 USDC liquidation nets around 9,800 USDC in profit, but only if the liquidator’s transaction beats all competitors to the block and the MEV environment does not spike gas prices.
Building for the future: Automation and protocol integration
The frontier of flash loan strategies involves tighter integration with PancakeSwap’s broader ecosystem. As limit orders, perpetuals trading, and staking features mature, flash loans can be used to unlock new use cases. A trader might use a flash loan to instantly rebalance across yield farming positions, ensuring optimal APR allocation without waiting for pool movements. Another might use flash loans to execute leveraged trades on perpetuals by borrowing capital, opening a large position, and closing it for profit—all within one transaction.
The infrastructure for this is still developing. Most sophisticated traders write custom smart contracts for each strategy because general-purpose flash loan routers do not yet capture all the nuanced logic. As the ecosystem matures and standardized flash loan frameworks improve, we can expect templates and libraries that make complex strategies more accessible. For now, the advantage goes to teams that understand both the token mechanics (swaps, pools, fees) and the smart contract execution model well enough to code custom solutions.
The deeper point is that flash loans represent a fundamental shift in DeFi capital efficiency. They eliminate the need to pre-position capital for trading strategies, lowering the barrier to sophisticated market participation. A trader with only gas fees in hand can participate in liquidation capture or arbitrage that once required millions in working capital. This democratizes certain trading activities while also increasing competition and reducing profit margins. The traders who thrive are those who model execution carefully, automate repetitive checks, and move fast when opportunities appear.
Frequently asked questions
What is the flash loan fee on PancakeSwap, and who receives it?
The standard flash loan fee on PancakeSwap’s liquidity pools is 0.05% of the borrowed amount. This fee is paid at the time of repayment and flows to the liquidity pool, effectively distributed to all liquidity providers as a return on their stake. The fee is enforced at the smart contract level and cannot be negotiated; failure to pay it causes the transaction to revert.
Can flash loans be used to attack DeFi protocols that use PancakeSwap prices?
Modern DeFi protocols use time-weighted average prices (TWAP) or decentralized price feeds from sources like Chainlink rather than spot prices, making them resistant to flash loan price manipulation. Flash loans execute within a single block and cannot move TWAP oracles. However, protocols that rely on spot prices or single-block price samples remain vulnerable; this is a protocol design flaw, not a flash loan weakness.
Do I need to write smart contract code to use flash loans?
Yes, flash loans require smart contract logic. There is no UI button on PancakeSwap’s DEX app to trigger a flash loan; you must write a contract that calls the flashLoan function, executes your strategy, and repays the amount plus the fee. Most flash loan users deploy custom contracts on testnets first, simulate execution, and then deploy to mainnet. Solidity knowledge and understanding of the constant product formula are prerequisites.


